How Does the IPO Book-Building Process Work? A Step-by-Step Guide for Investors
When a company decides to go public, one of the most important stages of the IPO is collecting investor demand and determining the offering price. This process is commonly known as book building.
For investors, understanding how book building works is essential. It explains how a company and its underwriters assess demand, determine the IPO price, allocate shares, and prepare for the stock’s first day of trading.
However, the process is not identical in every country. In the United States, IPO book building is largely managed by underwriters and their syndicates, with institutional investors playing an important role in price discovery and allocation. Retail investors may participate through selected brokerage firms, but access and allocation policies vary.
This guide explains the process from an investor’s perspective, using the U.S. IPO market as its primary reference while highlighting the differences investors may encounter in other markets.
30-Second Summary: How Does IPO Book Building Work?
- Book building is the process of gathering investor interest to help determine an IPO’s offering price and share allocation.
- The company appoints underwriters, who organize the offering and communicate with potential investors.
- Investors provide indications of interest, including the number of shares they may wish to purchase and, in some processes, the price they are willing to pay.
- Underwriters assess demand, valuation, market conditions, and investor feedback.
- The company and underwriters determine the final offering price and the number of shares to be sold.
- Shares are allocated to investors according to the offering structure and the underwriters’ allocation decisions.
- Retail investors may not receive all the shares they request, and participation does not guarantee an allocation.
The key takeaway: book building helps determine the terms of an IPO, but strong demand does not guarantee that the stock is attractively priced or will perform well after listing.
1. What Is Book Building in an IPO?
Book building is a process used during an IPO to collect and evaluate investor demand before the final offering price is established.
When a company goes public, it needs to determine how many shares to offer and at what price. Setting the price too high may make it difficult to attract sufficient demand. Setting it too low may mean that the company raises less capital than it could have obtained.
To help balance these competing interests, the company works with investment banks, known as underwriters, to gather information from potential investors.
These investors communicate how many shares they might be interested in purchasing and, depending on the process, the price levels they would consider acceptable.
The underwriters compile this information into an order book. The information helps the company and its advisers evaluate demand and negotiate the final IPO terms.
A simple example
Imagine a fictional company called CloudNova planning to sell 20 million shares in an IPO.
During the marketing and book-building process, potential investors express interest at different price levels:
| Indicative price | Potential demand |
|---|---|
| $18 per share | 30 million shares |
| $19 per share | 25 million shares |
| $20 per share | 21 million shares |
| $21 per share | 13 million shares |
This simplified illustration suggests that demand remains above the 20 million shares being offered at prices up to $20, but falls below the available supply at $21.
The company and underwriters could consider this information when negotiating the final offering price. The actual process is more complex: investor demand is not a simple guarantee of completed purchases, and pricing also depends on valuation, market conditions, investor quality, and the terms of the offering.
2. Why Is Demand Collected Before an IPO?
Book building serves several purposes for companies, underwriters, and investors.
Price discovery
The first objective is to estimate the price at which investors are willing to purchase the shares.
A company’s valuation may be based on financial performance, growth expectations, comparable companies, and other factors. But the market’s willingness to pay also matters.
Collecting investor feedback helps the company and underwriters understand whether the proposed valuation is likely to attract sufficient demand.
Measuring investor interest
The order book provides information about the level of interest in the offering. Underwriters can assess whether demand is concentrated among a few large investors or spread across a broader investor base.
They may also evaluate the investment horizon and characteristics of potential purchasers, not just the number of shares requested.
Determining offering size and pricing
Demand information can influence the final offering price and, in some circumstances, the number of shares offered.
If demand is weaker than expected, the company may need to reconsider its valuation or offering structure. If demand is strong, it may have greater flexibility, although the final decision still depends on market conditions and the company’s objectives.
Planning share allocation
Book building also helps underwriters determine how shares should be distributed among participating investors, subject to applicable rules and the offering arrangements.
3. Who Participates in the IPO Book-Building Process?
Book building involves several parties. Understanding their roles helps investors see why not every participant has the same access to IPO shares.
The issuing company
The issuer is the company offering its shares to the public. It works with underwriters to prepare the IPO, determine the number of shares to be offered, and agree on the final offering terms.
Lead underwriters
The lead underwriter, often an investment bank, coordinates the IPO process. Its responsibilities may include advising the company on valuation, preparing the offering, organizing investor presentations, collecting demand indications, and managing share allocation.
Large IPOs may involve multiple lead underwriters and additional investment banks.
The underwriting syndicate
An underwriting syndicate is a group of investment banks and broker-dealers participating in the distribution of the IPO shares.
The lead underwriter typically coordinates the syndicate and manages the broader offering process. Other members may help market and distribute the shares to their investor clients.
Institutional investors
Institutional investors may include mutual funds, pension funds, insurance companies, asset managers, and other professional investment organizations.
They often play an important role in the book-building process because they can evaluate the company in detail and submit substantial indications of interest.
Individual or retail investors
Retail investors are individuals who invest through brokerage accounts. Their access to IPO shares varies by offering and brokerage firm.
Some brokerage firms provide eligible customers with opportunities to participate in selected IPOs. Others may not offer direct IPO access to all clients.
4. How Does the IPO Book-Building Process Work Step by Step?
Although the details vary by offering, a typical U.S. IPO follows a sequence of stages.
Step 1: The company selects its underwriters
Before launching an IPO, the company appoints one or more investment banks to manage the offering.
The underwriters advise on the IPO structure, valuation, timing, share count, and investor marketing strategy.
They also coordinate with legal advisers, accountants, and other professionals involved in preparing the registration statement and prospectus.
Step 2: The company prepares and files its registration statement
For many U.S. IPOs, the company files a registration statement with the Securities and Exchange Commission (SEC), commonly using Form S-1.
The registration statement includes information about the company’s operations, financial statements, management, ownership structure, offering terms, and risk factors.
Investors should understand that an SEC filing is not an endorsement of the company or a guarantee that the investment is suitable.
Investors can find public registration statements and related filings through the SEC’s EDGAR database.
Step 3: The preliminary prospectus is made available
As the offering progresses, investors receive access to preliminary offering information, often through a preliminary prospectus.
This document may include an indicative price range, the number of shares expected to be offered, financial information, and the main risks associated with the company.
The preliminary prospectus is an important research document, but some details may change before the final offering terms are established.
Step 4: The company and underwriters conduct a roadshow
A roadshow is a marketing process during which company executives present the business to potential investors.
Management typically explains the company’s strategy, market opportunity, financial performance, competitive position, and future plans.
Institutional investors may ask questions about revenue growth, margins, customer concentration, cash flow, competition, and risks.
These discussions help investors evaluate the offering and allow underwriters to gather feedback about demand and valuation.
Step 5: Investors submit indications of interest
During book building, potential investors communicate their interest in purchasing shares.
An indication of interest may include the number of shares an investor is considering and, where applicable, the price level at which the investor would be willing to participate.
In the U.S. market, these indications are generally collected by underwriters and participating brokerage firms from investors they approach or serve.
An indication of interest should not be confused with a guaranteed allocation or a completed purchase. The investor may need to reconfirm interest once the final price and offering terms are known.
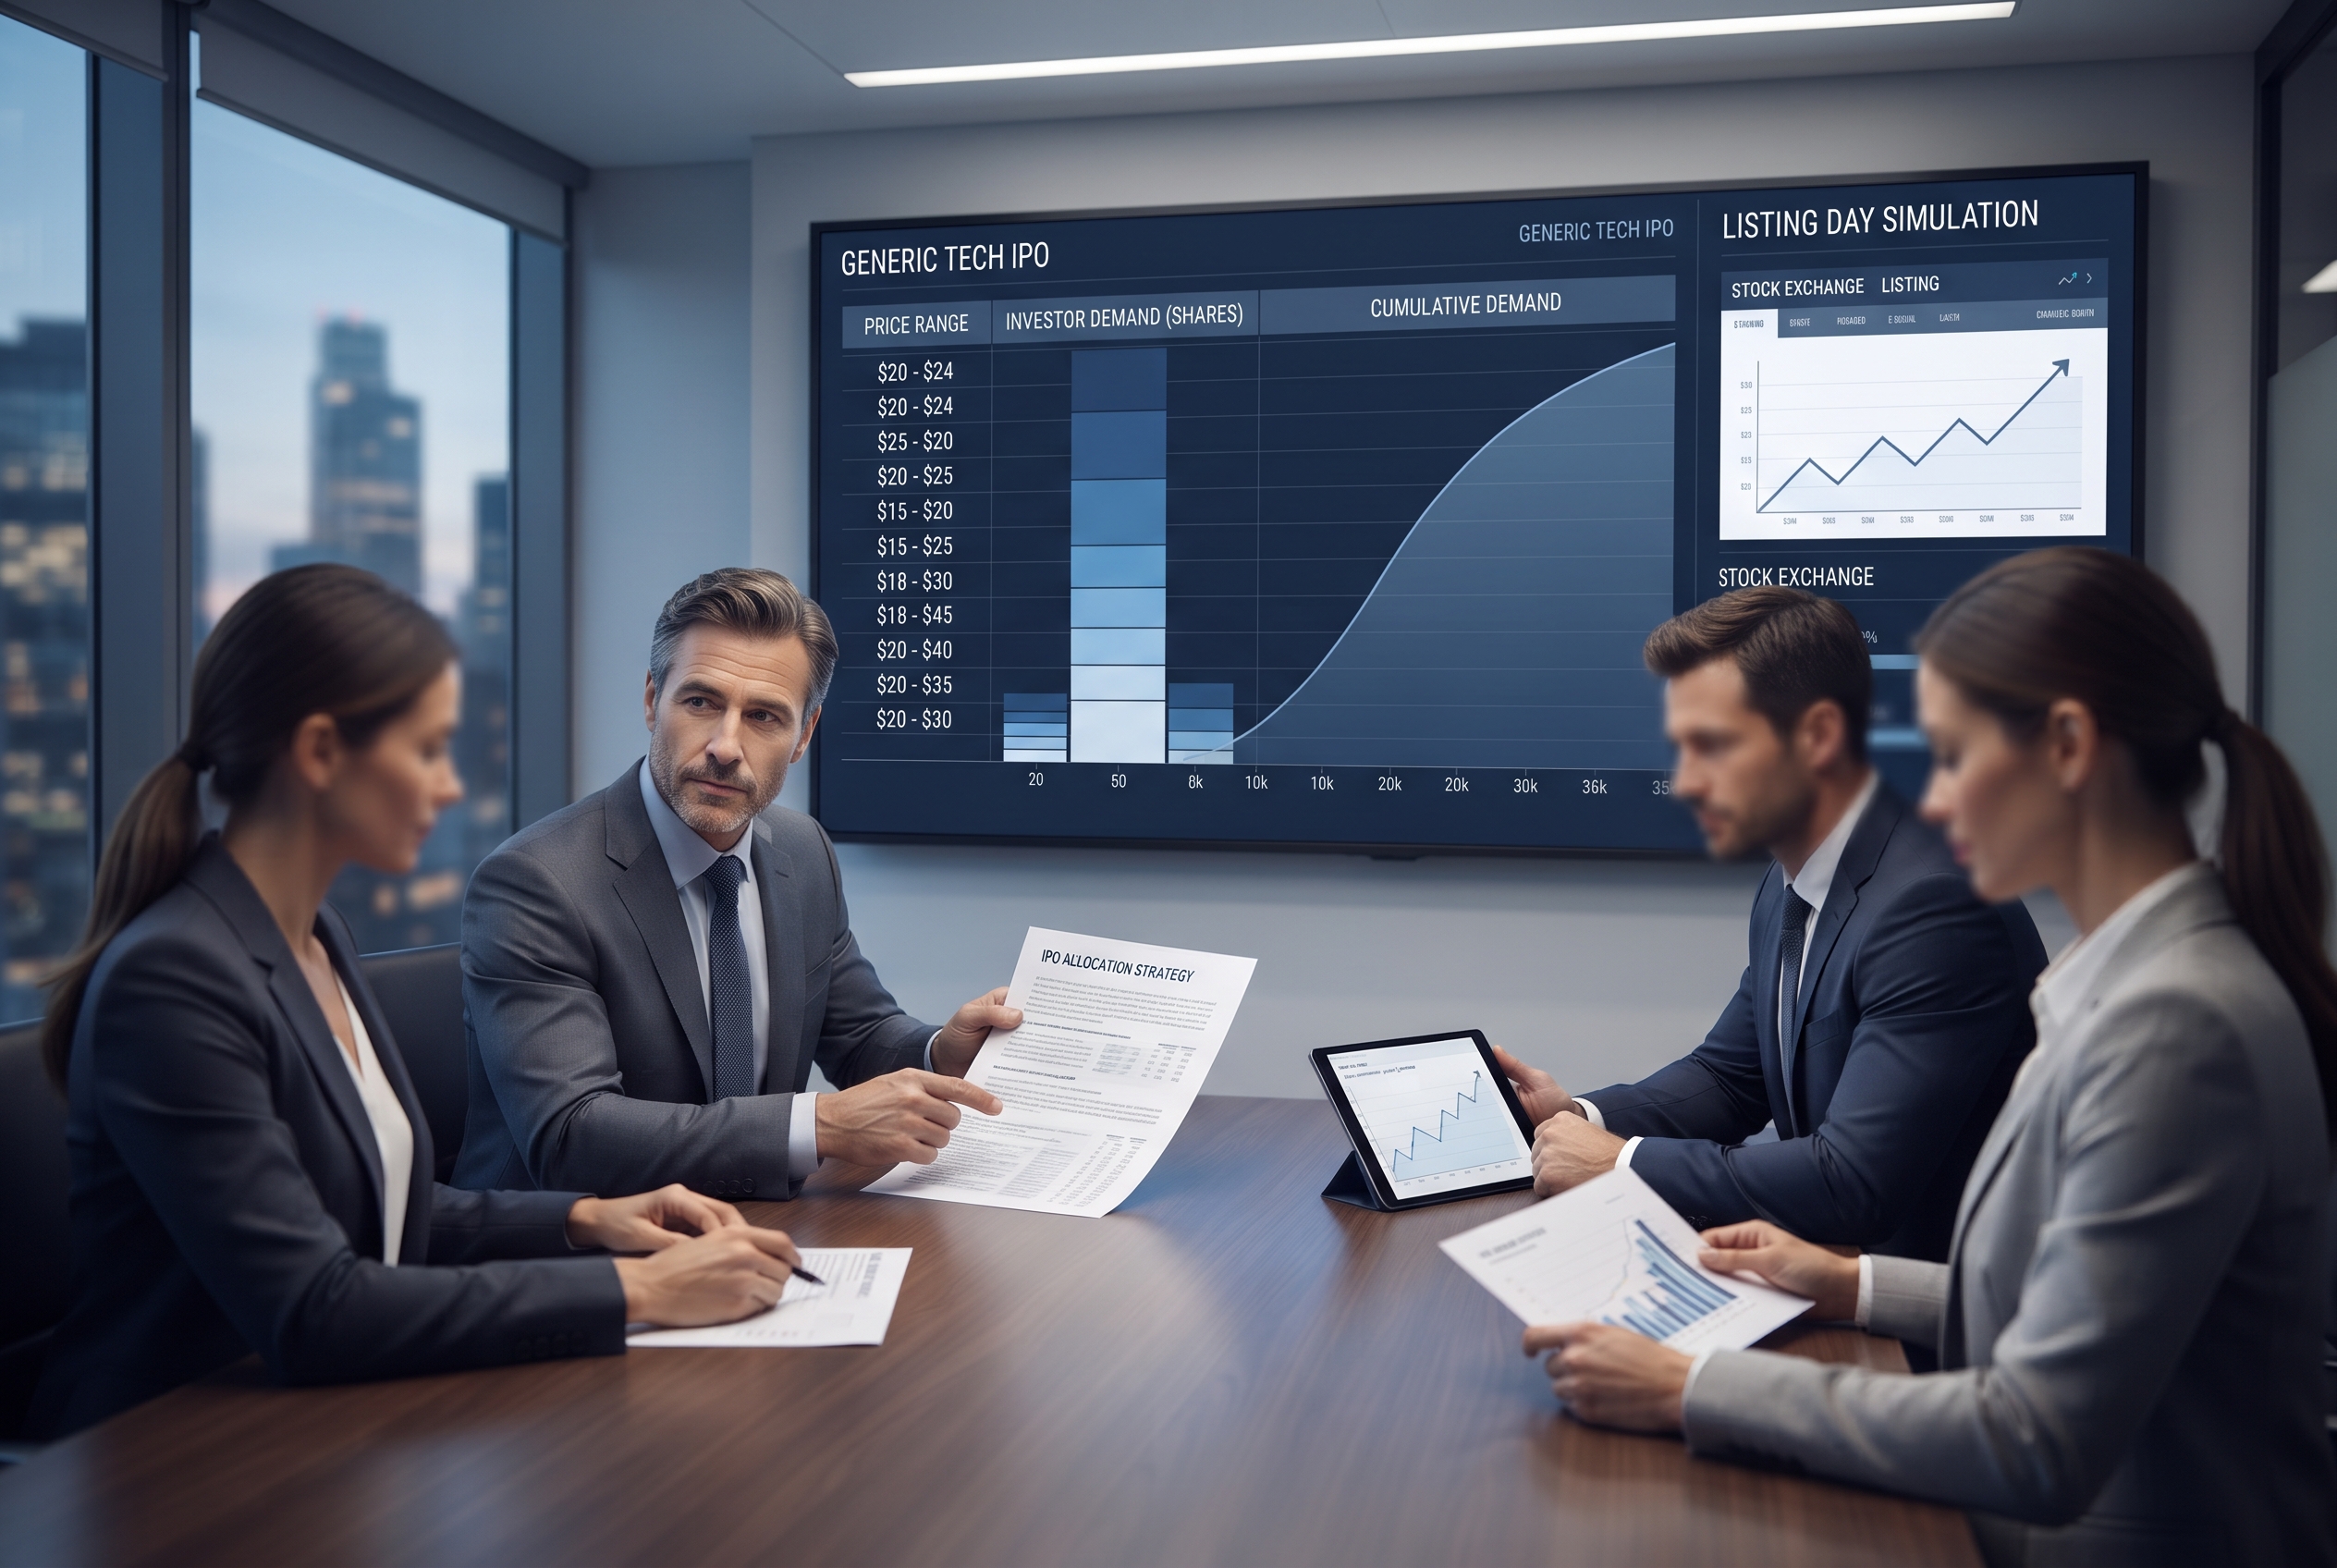
Step 6: Underwriters analyze the order book
The underwriters review the indications of interest and assess the overall demand profile.
They may consider:
- The total number of shares investors have indicated interest in purchasing.
- The price levels at which demand is strongest.
- The types of investors participating in the offering.
- The concentration of demand among large investors.
- Market conditions and the valuation of comparable companies.
- Feedback received during the roadshow.
Importantly, the order book is not simply a list of guaranteed orders. Indications can change, and the final allocation may differ from the preliminary demand information.
Step 7: The final IPO price is determined
After evaluating demand and market conditions, the company and underwriters agree on the final offering price and the number of shares to be sold.
The final price reflects a combination of valuation analysis, investor demand, negotiations, and the company’s capital-raising objectives.
The price may be within the preliminary range, above it, or below it, depending on the offering and applicable procedures.
Step 8: Shares are allocated to investors
Once the offering price is established and the relevant registration statement becomes effective, the allocation process can be completed.
Underwriters distribute shares among purchasers based on the offering structure and allocation decisions. Retail investors participating through brokerage programs may receive all, some, or none of the shares they requested.
Step 9: The company lists on the stock exchange
After pricing and allocation, the company’s shares begin trading on the selected exchange, subject to the required regulatory and exchange procedures.
Once public trading begins, the market price is determined by buyers and sellers. It can be higher or lower than the IPO offering price.
5. What Is the Difference Between Book Building and a Fixed-Price IPO?
Investors may encounter different pricing structures depending on the country and the offering.
In a fixed-price offering, the price is established before investors submit their applications. In a book-built offering, investor demand is collected and considered when determining the final price.
| Feature | Fixed-price offering | Book-built offering |
|---|---|---|
| Price determination | Price is set in advance. | Final price is determined after demand is assessed. |
| Investor input | Investors generally apply at the announced price. | Investor demand and, where applicable, price indications contribute to price discovery. |
| Demand information | Demand is observed during the subscription or sales period. | Demand is collected and analyzed during the book-building process. |
| Price flexibility | Usually limited once the offer price is announced. | May allow adjustments within the offering framework. |
| Allocation | Depends on the applicable distribution rules. | Depends on the offering structure and allocation decisions. |
These are general descriptions. The precise procedures differ by jurisdiction, exchange, and offering structure. Some markets also use hybrid approaches.
6. How Is the Final IPO Price Determined?
Price discovery is one of the most important functions of book building. The objective is to establish an offering price that balances the company’s capital-raising needs with the demand of potential investors.
Several factors influence the final price.
Company valuation
Underwriters and investors evaluate the company’s financial performance, growth expectations, competitive position, and risks.
Common valuation measures include:
- Price-to-Earnings (P/E): Useful for companies with meaningful earnings.
- Price-to-Sales (P/S): Often considered for companies with high revenue growth but limited or negative earnings.
- EV/EBITDA: A measure used to compare enterprise value with operating earnings before certain expenses.
- Price-to-Book (P/B): Potentially relevant for financial institutions and asset-intensive businesses.
Investors should compare a company with genuinely comparable businesses rather than relying on a single valuation multiple.
Investor demand
Demand at different price levels provides information about how much investors may be willing to pay.
However, strong demand should not automatically be interpreted as evidence that the IPO is undervalued. Demand may also reflect market enthusiasm, limited share supply, or expectations that are already reflected in the offering price.
Market conditions
Interest rates, equity-market volatility, sector performance, and investor sentiment can influence the price investors are willing to pay.
A company may have strong fundamentals but face weaker IPO demand during a period of market uncertainty.
Offering size and share supply
The number of shares offered and the proportion of the company being sold can also affect pricing.
A relatively small public float may create different trading dynamics from an offering with a larger number of freely tradable shares.
7. How Are IPO Shares Allocated?
After the final offering price is established, shares must be distributed among investors.
There is no single allocation formula that applies to every IPO in every country. Allocation depends on the regulatory framework, offering documents, investor categories, underwriting arrangements, and brokerage policies.
Allocation in the United States
In many U.S. IPOs, underwriters allocate shares among institutional and other eligible purchasers. The allocation process is managed by the underwriting syndicate, subject to applicable securities laws and the terms of the offering.
Retail investors may be able to participate through brokerage firms that have access to the offering. Each firm may have eligibility criteria, account requirements, deadlines, and allocation policies.
Some brokerages may consider factors such as account eligibility, available share allocations, and their own program rules. Investors should review the specific brokerage terms rather than assume that all firms use the same method.
Why might a retail investor receive fewer shares than requested?
- The IPO may attract more demand than the number of shares available.
- The brokerage may receive a limited allocation from the underwriting syndicate.
- The investor may not meet the brokerage’s eligibility requirements.
- The brokerage may apply its own allocation methodology.
- The investor’s indication of interest may not be confirmed as a final order.
Submitting a request for shares does not guarantee that the investor will receive them.
Equal and proportional distribution: why market rules matter
Some markets use specific retail allocation categories, including equal or proportional distribution. These rules should not be assumed to apply to U.S. IPOs.
In the U.S., retail access and allocation are generally determined through the offering’s underwriting arrangements and participating brokerage programs. Investors should read the relevant offering information and brokerage disclosures to understand how shares may be distributed.
8. What Happens If an IPO Is Oversubscribed?
An IPO is described as oversubscribed when indications of interest exceed the number of shares available at the relevant offering terms.
For example, imagine a company offering 10 million shares. During book building, investors submit indications of interest totaling 30 million shares.
In this simplified example, demand is three times the number of shares offered.
However, oversubscription does not mean that every investor will receive one-third of the shares requested. The final allocation depends on the offering structure and the underwriters’ decisions.
Oversubscription can indicate strong investor interest, but it should not be treated as proof of a company’s financial strength or an attractive valuation.
9. What Happens If an IPO Receives Weak Demand?
Not every IPO attracts sufficient demand. If investor interest is weaker than expected, the company and underwriters may need to reconsider the offering terms.
Depending on the circumstances and applicable rules, possible outcomes include:
- Reducing the final offering price.
- Changing the number of shares offered.
- Revising the offering timetable.
- Postponing or withdrawing the IPO.
A reduced offering price may make the valuation more attractive, but it does not automatically make the company a good investment. Investors should investigate why demand was weak and whether the original concerns remain relevant.
10. What Should Retail Investors Do During the Book-Building Period?
Retail investors may have less direct influence over IPO pricing than institutional investors, but they can still make informed decisions about whether to participate.
Read the latest prospectus
Review the company’s business model, financial statements, risk factors, ownership structure, and use of proceeds.
Understand the offering price range
If an indicative price range is provided, compare the implied valuation with relevant public companies and the issuer’s financial performance.
Check your brokerage’s IPO participation rules
Confirm whether your brokerage offers access to the specific IPO. Review eligibility criteria, deadlines, account requirements, and any applicable fees or restrictions.
Understand what an indication of interest means
Do not assume that an indication of interest is a confirmed purchase. Check whether you need to reconfirm your order after the final price is announced.
Decide how much risk you are willing to take
Newly listed shares can experience substantial price movements. Determine the maximum amount you are prepared to invest before submitting an indication or order.
Avoid making decisions based only on oversubscription
High demand may attract attention, but it does not replace fundamental analysis. Consider the company’s valuation, cash flow, competitive position, and risks.
11. A Practical Example: Following a Fictional IPO from Demand to Listing
Imagine that a fictional company called BrightGrid, which develops software for energy-management systems, plans to go public in the United States.
The company intends to offer 15 million shares. Its underwriters initially discuss an indicative price range of $22 to $26 per share.
During the roadshow, management presents its business model, revenue growth, customer base, and expansion plans to potential investors.
Institutional investors and participating brokerage clients provide indications of interest. The underwriters analyze the order book and receive feedback on the proposed valuation.
Suppose the final offering price is set at $25 per share. The gross proceeds from selling 15 million primary shares would be:
15 million shares × $25 = $375 million
This is a simplified illustration and excludes underwriting discounts, expenses, and any secondary shares sold by existing shareholders.
After the final price is established, shares are allocated to participating investors. Some retail investors may receive their full requested allocation, others may receive fewer shares, and some may receive none.
When BrightGrid begins trading, its market price is determined by actual buying and selling activity. It could rise above $25, remain close to the offering price, or fall below it.
The example demonstrates why investors should distinguish between three separate stages:
- Demand collection: Investors communicate preliminary interest.
- Pricing and allocation: The company and underwriters finalize the offering terms and distribute shares.
- Public trading: The market determines the share price after listing.
These stages are connected, but they are not interchangeable. Strong demand during book building does not guarantee a positive trading performance.
12. Common Misunderstandings About IPO Book Building
Thinking that an indication of interest guarantees shares
An indication of interest is preliminary. The investor may not receive an allocation and may need to confirm participation after pricing.
Assuming oversubscription means guaranteed first-day gains
Oversubscription measures demand relative to supply. It does not predict the stock’s future performance.
Believing that the IPO price is always the company’s fair value
The offering price is negotiated using valuation analysis and market demand. It can differ significantly from the price at which shares trade after listing.
Assuming all brokerages provide equal IPO access
Brokerage firms differ in their relationships with underwriters, participation programs, eligibility requirements, and available allocations.
Confusing book building with ordinary stock-market trading
Book building takes place before the public listing and helps determine offering terms. Once trading begins, prices are determined by market orders and available liquidity.
13. IPO Book-Building Checklist for Investors
Before participating in an IPO, use this checklist to review both the company and the application process.
- ☐ I understand what the company does and how it generates revenue.
- ☐ I have reviewed the latest prospectus or registration statement.
- ☐ I understand the company’s financial performance and major risks.
- ☐ I have evaluated the proposed IPO valuation against relevant competitors.
- ☐ I understand the purpose of the capital being raised.
- ☐ I know how many shares are being offered and whether existing shareholders are selling.
- ☐ I understand the preliminary price range and final pricing process.
- ☐ I know whether my brokerage provides access to the IPO.
- ☐ I understand the difference between an indication of interest and a confirmed order.
- ☐ I have checked the brokerage’s deadlines and allocation policies.
- ☐ I understand that I may receive fewer shares than requested or no shares.
- ☐ I have determined how much I can afford to invest.
- ☐ I am prepared for the possibility that the stock may fall below its IPO price.
Conclusion: Understanding Book Building Helps Investors Make Better IPO Decisions
Book building is a central part of many IPOs. It allows companies and underwriters to collect investor demand, assess valuation expectations, determine the offering price, and organize share allocation.
For investors, understanding the process helps explain why IPO prices change before listing, why some offerings attract strong demand, and why retail investors may receive fewer shares than they request.
However, book building should not be mistaken for a guarantee of investment quality. An oversubscribed IPO can still be expensive, while an offering with weaker demand may still deserve further analysis.
The most disciplined approach is to understand both the mechanics of the offering and the fundamentals of the company. Read the prospectus, evaluate the valuation, check the allocation rules, and decide whether the investment fits your financial objectives.
Ultimately, the purpose of understanding book building is not simply to improve the chances of receiving IPO shares. It is to make a better-informed decision about whether those shares are worth owning.
Frequently Asked Questions About IPO Book Building
1. What does book building mean in an IPO?
Book building is the process of collecting investor indications of interest to help a company and its underwriters determine the final IPO price and share allocation.
2. How long does IPO book building take?
The duration varies by market and offering. In the United States, investor demand is typically gathered during the IPO marketing and roadshow period. There is no single fixed duration for every IPO.
3. Who determines the final IPO price?
The issuing company and its underwriters agree on the final offering price after considering valuation analysis, investor demand, market conditions, and the offering structure.
4. What is an IPO order book?
An IPO order book is a record of indications of interest collected from potential investors. It helps underwriters assess demand at different price levels and understand investor participation.
5. What is an indication of interest?
An indication of interest is a preliminary expression that an investor may want to purchase a certain number of shares, sometimes at a specified price. It does not guarantee an allocation or completed transaction.
6. Does an indication of interest guarantee IPO shares?
No. The final allocation depends on the offering terms, available shares, underwriting arrangements, and brokerage policies. Investors may receive all, some, or none of the shares they requested.
7. What is the difference between book building and a fixed-price IPO?
In a fixed-price offering, the price is established before applications are submitted. In book building, investor demand is collected and considered when determining the final offering price.
8. What does an oversubscribed IPO mean?
An IPO is oversubscribed when indications of interest exceed the number of shares available at the relevant offering terms. It indicates demand but does not guarantee positive stock performance.
9. What happens if an IPO is undersubscribed?
If demand is weaker than expected, the company and underwriters may reconsider the price, offering size, or timetable. In some cases, the offering may be postponed or withdrawn.
10. Can retail investors participate in U.S. IPOs?
Yes, some brokerage firms provide eligible retail customers with access to selected IPOs. Availability and allocation policies vary by brokerage and offering.
11. Why do institutional investors play an important role in book building?
Institutional investors often have research teams and the ability to evaluate companies in detail. Their indications of interest can provide underwriters with information about demand and valuation expectations.
12. What is a roadshow in an IPO?
A roadshow is a marketing process in which company executives present the business and its investment proposition to potential investors, often with the support of underwriters.
13. Can the IPO price change during book building?
Depending on the offering structure and applicable rules, the preliminary price range or proposed terms may be revised before the final offering price is established.
14. What happens after the final IPO price is determined?
The underwriters complete the allocation process after the relevant registration statement becomes effective and the offering terms are finalized. The shares then begin trading once listing and settlement procedures are completed.
15. Why might two investors receive different IPO allocations?
Allocation can depend on the brokerage’s available shares, investor eligibility, the offering structure, and allocation policies. Different brokerage firms may have different access and procedures.
16. Is a highly oversubscribed IPO always a good investment?
No. Oversubscription reflects demand relative to supply, not the company’s intrinsic value. Investors should still analyze financial performance, valuation, competition, and risk.
17. Can the stock price fall below the IPO offering price?
Yes. Once public trading begins, the market price can move above or below the offering price depending on supply, demand, company developments, and market conditions.
18. Where can I read the prospectus for a U.S. IPO?
Investors can search for registration statements and prospectuses through the SEC’s EDGAR database. Brokerage firms participating in an offering may also provide relevant offering documents.
19. Does book building happen in every IPO?
No. IPO pricing and distribution methods vary across markets. Some offerings use book building, while others use fixed-price or alternative mechanisms. The applicable process should be described in the offering documents.
20. What is the most important thing to remember about book building?
Book building is a price-discovery and allocation process, not a measure of guaranteed investment success. Investors should evaluate the company and its valuation independently before participating.
Disclaimer
This article is for educational and informational purposes only. It does not constitute investment, legal, tax, or financial advice, or a recommendation to buy or sell any security. IPO investments involve risks, including the potential loss of principal. Procedures, eligibility requirements, and allocation policies vary by jurisdiction, offering, and brokerage firm. Investors should review the relevant offering documents and consult qualified professionals where appropriate.