What Are the Risks of Investing in Stocks? A Complete Guide for Investors
Stocks have historically been one of the most powerful tools for building long-term wealth. They offer investors the opportunity to participate in the growth of businesses, benefit from capital appreciation, and potentially receive dividend income.
But there is another side of the equation that every investor needs to understand:
Stock investing involves real financial risk.
A stock can lose 10%, 30%, 50%, or even more of its value. In extreme cases, an investor can lose most or all of the money invested in an individual company.
The important question, therefore, is not whether stocks are risky. They are.
The more useful question is:
What types of risks do stocks carry, and how can investors manage them without abandoning the long-term growth potential of equities?
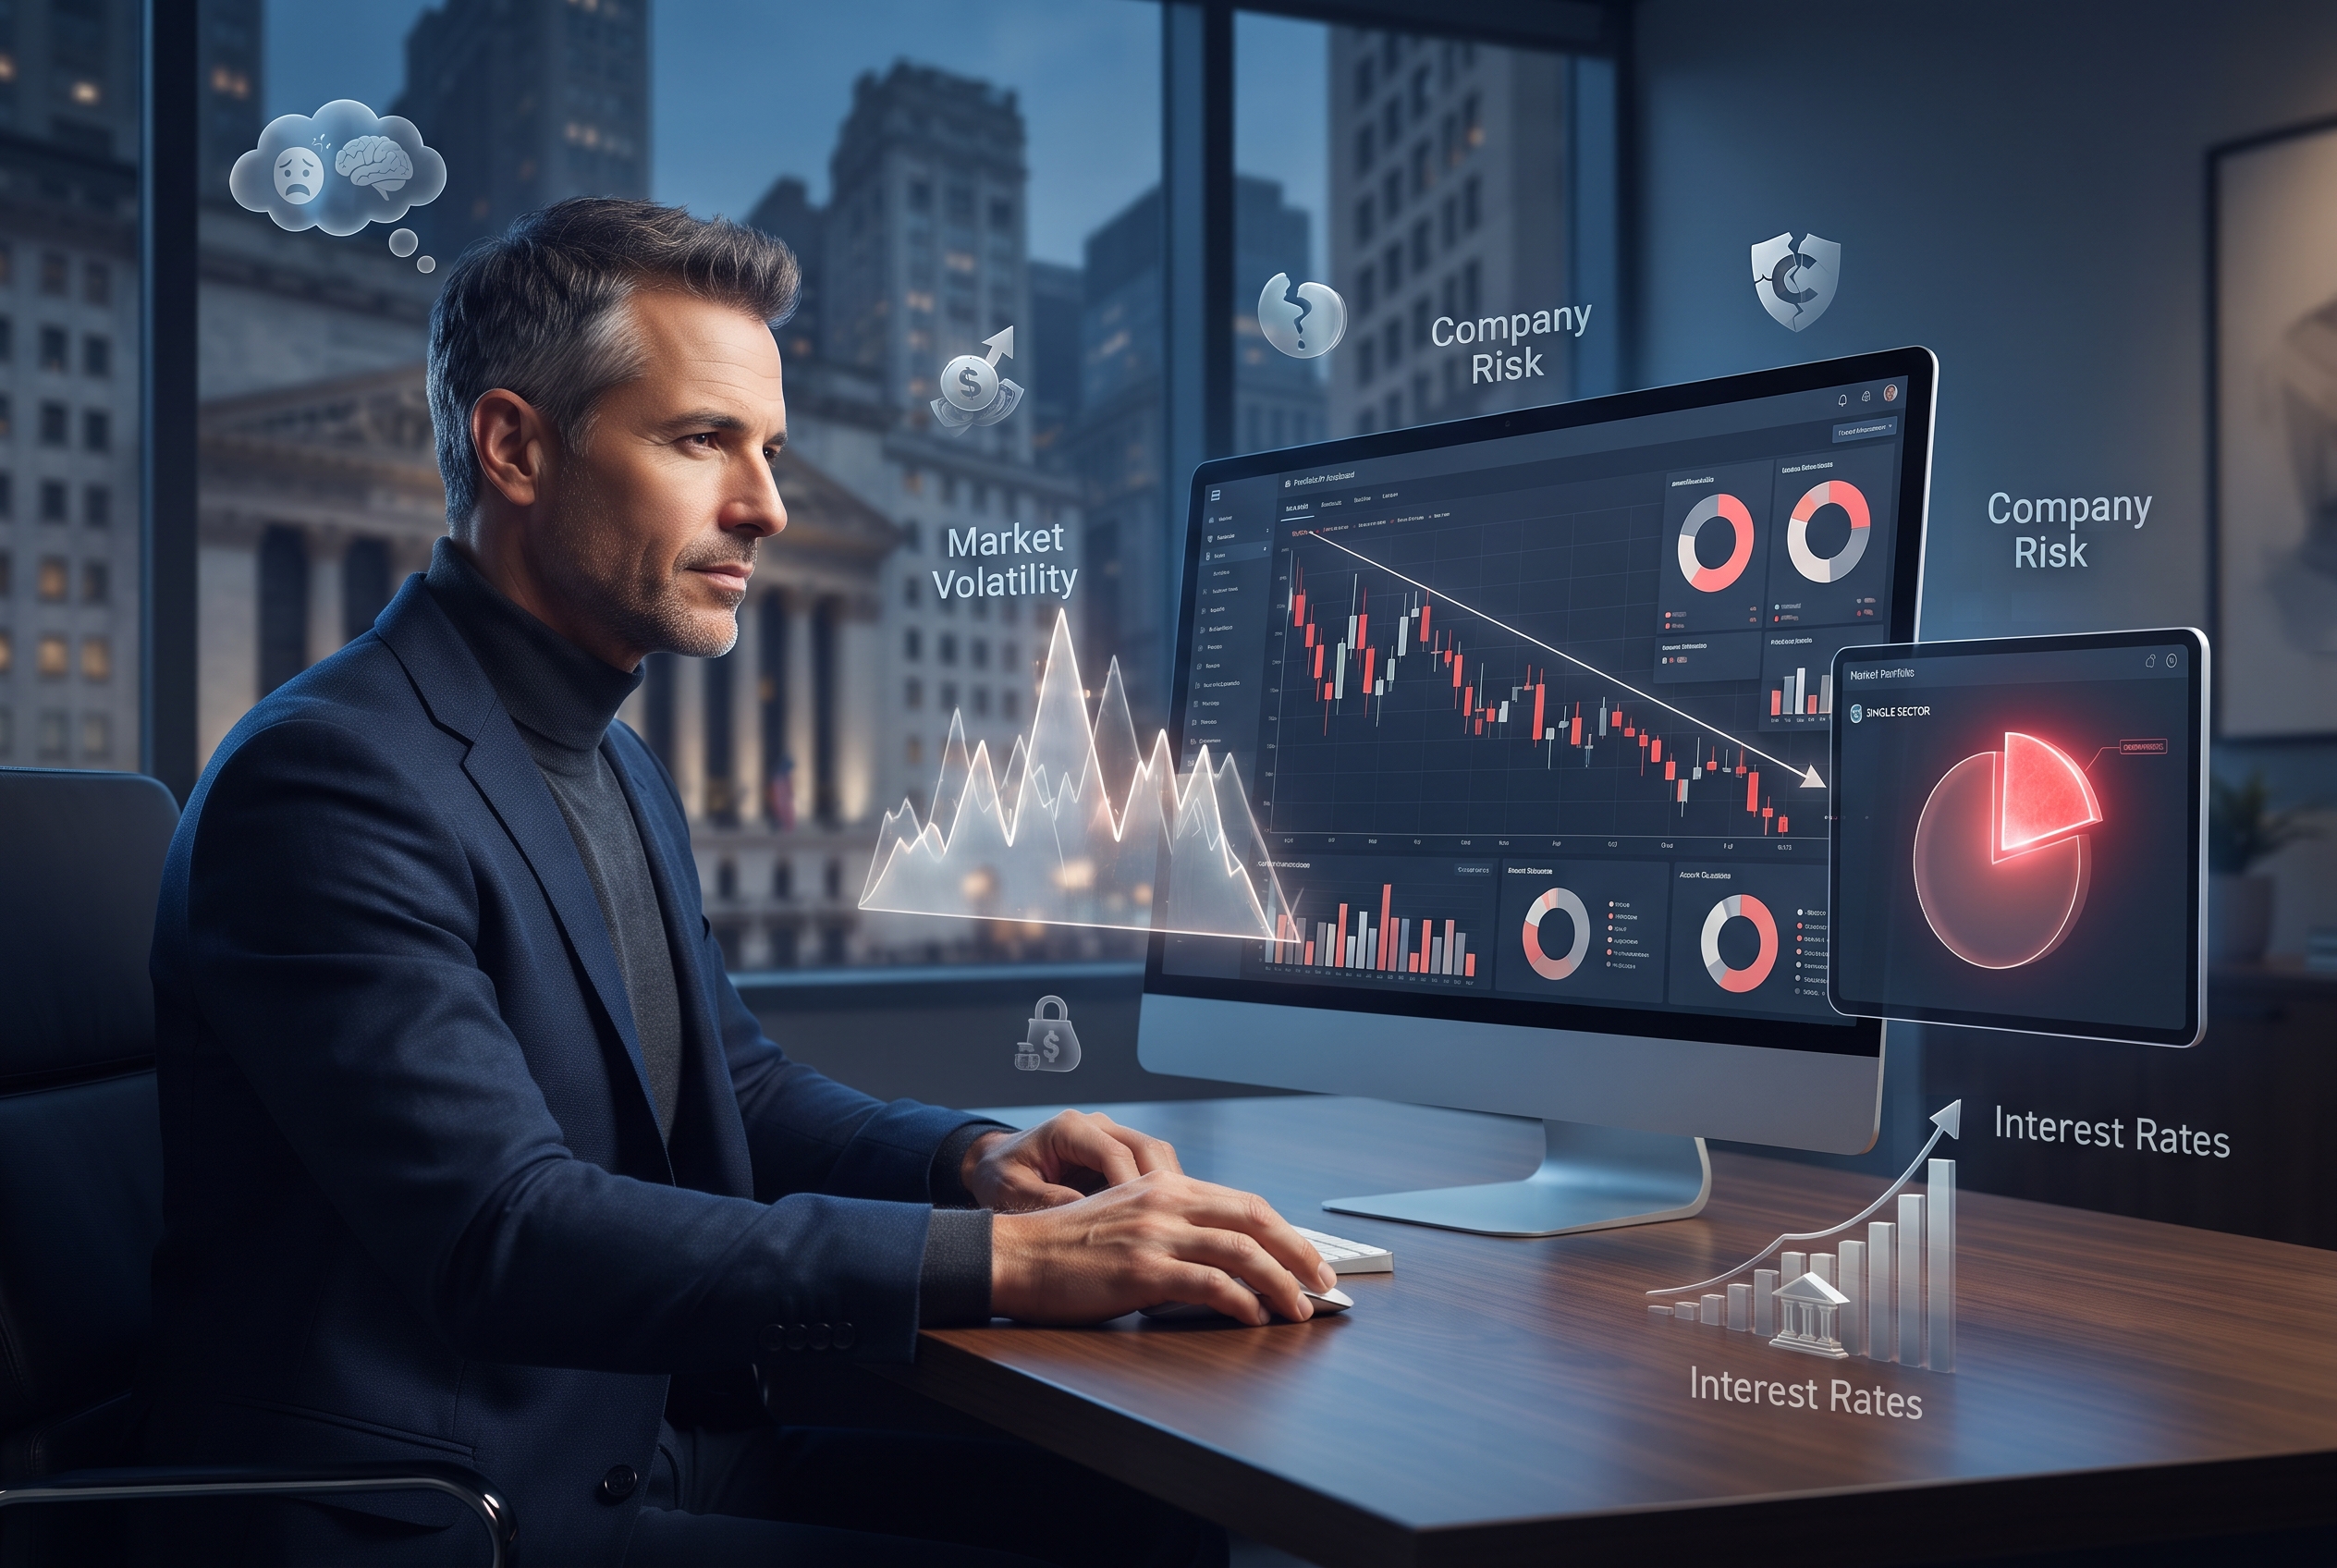
This guide examines the major risks of stock investing from the perspective of U.S. and global investors, including market risk, company-specific risk, concentration risk, valuation risk, liquidity risk, inflation risk, interest-rate risk, behavioral risk, and the danger of investing money that may be needed too soon.
30-Second Summary
- Stocks can lose money. There is no guaranteed return, even when investing for the long term.
- Market risk can cause broad stock markets to decline because of recessions, inflation, interest rates, geopolitical events, or changing investor expectations.
- Company-specific risk comes from problems affecting an individual business, such as weak earnings, excessive debt, fraud, poor management, or technological disruption.
- Concentration risk becomes dangerous when too much of your portfolio depends on one stock, sector, country, or theme.
- Valuation risk means even an excellent company can be a poor investment if you pay too much for its future growth.
- Liquidity risk can make it difficult to sell an investment quickly at a reasonable price.
- Behavioral risk can cause investors to buy during excitement and sell during panic.
- Diversification, appropriate asset allocation, a sufficient time horizon, cash reserves, and disciplined portfolio management can help manage—but not eliminate—investment risk.
Why Are Stocks Risky?
When you buy a stock, you are purchasing an ownership interest in a business.
Your investment therefore depends partly on the success of that business and partly on what other investors are willing to pay for its shares.
If the company’s earnings, growth prospects, competitive position, or financial health deteriorate, its stock price may decline.
But the stock can also fall even when the company continues to perform reasonably well.
Why?
Because stock prices reflect expectations.
If investors expected a company to grow earnings by 30% and earnings grow by only 15%, the stock could fall even though the company is still profitable and growing.
This is one of the most important concepts in stock investing:
A good company is not automatically a good investment at any price.
Stocks also react to factors outside the control of individual companies, including interest rates, economic growth, inflation, geopolitical developments, currency movements, and changes in investor sentiment.
FINRA notes that stocks can lose value because of both broad market conditions and company-specific events, while concentration in a single investment can create additional risk.
The 10 Major Risks of Stock Investing
Stock market risk is not one single risk. It is a combination of different risks that can affect your portfolio in different ways.
| Risk | What It Means | Typical Example |
|---|---|---|
| Market Risk | The overall stock market declines | Recession causes broad indexes to fall |
| Company Risk | A specific business performs poorly | Earnings collapse or debt becomes unmanageable |
| Concentration Risk | Too much money depends on one investment or sector | 40% of portfolio in one technology stock |
| Valuation Risk | You pay too much for expected future earnings | High-growth stock misses expectations |
| Liquidity Risk | An investment is difficult to sell efficiently | Thinly traded small-cap stock |
| Interest-Rate Risk | Changing rates affect valuations | Higher rates pressure high-growth stocks |
| Inflation Risk | Inflation reduces real purchasing power | Investment return fails to outpace inflation |
| Currency Risk | Exchange-rate movements affect international investments | Dollar strengthens against a foreign currency |
| Behavioral Risk | Emotions lead to poor decisions | Selling after a market crash |
| Time-Horizon Risk | You need the money before the market recovers | Selling stocks to fund a near-term expense |
1. Market Risk
Market risk is the possibility that the overall stock market declines, causing many stocks to fall at the same time.
This is sometimes called systematic risk because it can affect a broad portion of the market rather than one specific company.
For example, stock prices may fall because of:
- A recession
- Rapidly rising interest rates
- Unexpected inflation
- Geopolitical conflict
- Financial-system stress
- Weak consumer spending
- Major changes in monetary policy
- Global economic deterioration
- A sharp decline in investor confidence
During such periods, even fundamentally strong companies can experience significant declines.
This is why diversification cannot completely protect an investor from a bear market.
If you own a diversified portfolio of U.S. stocks and the entire U.S. equity market declines, your portfolio can still fall.
Diversification is designed primarily to reduce concentration and company-specific risk, not eliminate broad market risk.
If you want to understand how experienced investors respond when markets fall, see our guide on what to do when the stock market falls.
2. Company-Specific Risk
Company-specific risk is the possibility that something goes wrong with the business you own.
Examples include:
- Weak sales
- Loss of major customers
- Product failures
- Accounting problems
- Management mistakes
- Excessive debt
- Regulatory action
- Lawsuits
- Cybersecurity incidents
- Technological disruption
- New competitors
- Supply-chain problems
- Loss of intellectual property
Imagine you invest $20,000 in one company because you believe its technology will dominate an emerging market.
Six months later, a competitor releases a superior product and the company’s growth expectations collapse.
The broader stock market may remain healthy while your investment falls 45%.
This is why individual stock investing requires understanding the underlying business—not simply following price charts or headlines.
3. Concentration Risk
Concentration risk occurs when too much of your wealth depends on a small number of investments, sectors, asset classes, or markets.
Suppose you have a $100,000 portfolio:
| Portfolio | Largest Position | Potential Problem |
|---|---|---|
| Portfolio A | $5,000 | Limited company-specific exposure |
| Portfolio B | $20,000 | Meaningful single-stock risk |
| Portfolio C | $50,000 | Very high concentration |
| Portfolio D | $80,000 | Extreme dependence on one company |
The larger the position, the more a single company’s problems can affect your financial future.
Concentration can also occur without realizing it.
For example, you might own:
- Individual technology stocks
- A technology-sector ETF
- A broad S&P 500 index fund
- Your employer’s technology stock
At first glance, you may think you own four different investments.
In reality, the same large technology companies may appear in several of them.
FINRA specifically warns that investors can face concentration risk through overlapping funds, sectors, geographic exposure, or individual securities.
Our guide to starting investing with a small amount of money explains why diversification matters even when your portfolio is relatively small.
4. Valuation Risk
One of the most misunderstood risks in stock investing is valuation risk.
A company can be excellent and still be a bad investment if its stock price already assumes unrealistic future growth.
Consider a simplified example.
Company A is growing revenue by 25% per year and has strong competitive advantages.
Investors become extremely optimistic and push the stock to a valuation that assumes decades of exceptional growth.
Then growth slows from 25% to 15%.
The company is still growing rapidly, but the stock falls because investors revise their expectations.
This is why stock analysis should consider both:
- Business quality
- Price paid for that business
Valuation metrics can include:
- Price-to-earnings ratio (P/E)
- Price-to-sales ratio (P/S)
- Price-to-book ratio (P/B)
- Enterprise value to EBITDA
- Free cash flow yield
- Dividend yield
None of these metrics should be used in isolation.
5. Volatility Risk
Volatility is the degree to which an investment’s price fluctuates over time.
A stock can move dramatically even without a permanent change in the underlying business.
For example, a stock trading at $100 could move to:
- $92 after a disappointing earnings report
- $108 after a positive analyst upgrade
- $96 after a broader market decline
- $115 after strong guidance
These short-term fluctuations can be uncomfortable.
But volatility and permanent loss are not identical.
A temporary decline can reverse. A permanent loss caused by business deterioration may not.
This distinction is particularly important for long-term investors.
6. Liquidity Risk
Liquidity refers to how easily you can buy or sell an investment without causing a significant change in its price.
Large, heavily traded companies generally have high liquidity.
Some small-cap or thinly traded stocks may have much lower liquidity.
Imagine you own a stock with very little trading volume.
During normal market conditions, you might be able to sell your shares without much difficulty.
But during a market panic, buyers may disappear or bid prices may fall sharply.
You may technically be able to sell—but only at a price substantially below what you expected.
Liquidity becomes particularly important if you may need your investment quickly.
This leads to an important principle:
Do not invest money in volatile assets if you may need to spend that money in the near future.
7. Interest-Rate Risk
Interest rates can have a significant influence on stock valuations.
When interest rates rise, several things can happen:
- Borrowing becomes more expensive for companies.
- Consumer borrowing may slow.
- Bond yields may become more attractive relative to stocks.
- Future corporate cash flows may be discounted at higher rates.
- High-growth companies can experience valuation pressure.
This does not mean that every rate increase causes stocks to fall.
The relationship is more complicated because economic growth, earnings expectations, inflation, and the reasons behind the rate change also matter.
For example, rising rates because the economy is exceptionally strong can produce a different market environment from rising rates because inflation is unexpectedly persistent.
8. Inflation Risk
Inflation affects stock investors in two important ways.
First, inflation reduces the purchasing power of money.
Second, high inflation can influence interest rates, consumer behavior, corporate costs, and valuation multiples.
Consider an investment that produces a nominal return of 6% while inflation is 5%.
The nominal return appears positive, but the investor’s real purchasing-power gain is much smaller.
Some businesses can pass higher costs to customers and maintain their margins. Others cannot.
That means inflation can affect companies very differently.
For a deeper discussion, see our guide on protecting your money from inflation.
9. Currency and International Risk
Investors who own international stocks face another layer of uncertainty: currency movements.
Suppose a U.S. investor owns shares of a European company.
The company’s stock may rise 10% in euros.
But if the euro weakens significantly against the U.S. dollar, the investor’s dollar-denominated return may be much lower.
International companies can also be affected by:
- Political instability
- Different regulatory systems
- Trade restrictions
- Capital controls
- Economic instability
- Different accounting standards
- Geopolitical tensions
International diversification can be valuable, but investors should understand that it introduces additional sources of risk.
10. Behavioral Risk
Perhaps the most underestimated risk is not the market itself.
It is the investor.
Investors often make their worst decisions when emotions are strongest.
Common behavioral mistakes include:
- Buying because everyone else is buying
- Selling after a large decline
- Chasing stocks that recently performed well
- Checking prices constantly
- Trying to predict every market move
- Overtrading
- Refusing to admit an investment thesis is wrong
- Holding a losing stock simply because of the purchase price
Fear and greed can turn temporary market volatility into permanent investment losses.
This is why investment psychology is an essential part of risk management.
Can Long-Term Investing Eliminate Stock Risk?
No.
This is a critical distinction.
A longer investment horizon can make short-term volatility easier to tolerate, but it does not make stocks risk-free.
Even a diversified stock portfolio can experience substantial declines over long periods.
FINRA explicitly notes that stocks remain risky investments even over long horizons. A long holding period may improve the probability of achieving positive outcomes historically, but it does not guarantee that an investor will avoid losses.
Therefore, the correct statement is:
Time can help investors manage volatility, but time does not eliminate investment risk.
What Happens If You Need the Money During a Market Crash?
This is where time-horizon risk becomes extremely important.
Imagine you are saving $100,000 for a house purchase that you expect to make in six months.
Putting the entire amount into stocks may expose you to a major problem.
If the market falls 25% just before you need the money, you may be forced to sell at a loss.
The investment did not necessarily fail.
The problem was that the investment did not match the timing of the financial goal.
For this reason, asset allocation should reflect both risk tolerance and time horizon. Investor.gov emphasizes that investors with shorter time horizons may prefer less volatile investments, while longer horizons may allow greater tolerance for volatility.
This is also why maintaining appropriate cash reserves is important when investing.
Our guide on why investors need cash when investing explores this issue in greater detail.
How Diversification Helps Manage Stock Risk
Diversification means spreading investments across different securities, sectors, industries, geographies, and sometimes asset classes.
Suppose you own one company.
If that company experiences a catastrophic business problem, your portfolio can be devastated.
Now suppose you own 100 companies through a broad-market fund.
A single company’s collapse may have a much smaller impact on the total portfolio.
That is the basic benefit of diversification.
However, diversification has limits.
If you own 20 technology stocks, you are diversified across companies but potentially concentrated in one industry.
If you own five ETFs that all heavily invest in the same mega-cap companies, you may have more overlap than you realize.
FINRA and Investor.gov both emphasize diversification across and within asset classes as an important risk-management tool.
Individual Stocks vs. Diversified Funds
| Risk Dimension | Individual Stock | Diversified Fund |
|---|---|---|
| Company-specific risk | High | Generally lower |
| Market risk | High | Still present |
| Concentration risk | Potentially high | Usually lower if broadly diversified |
| Research requirement | Higher | Generally lower |
| Control | High | Lower |
| Potential diversification | Depends on portfolio | Often high |
| Volatility | Can be very high | Depends on fund |
A diversified fund is not automatically low risk.
A technology ETF, emerging-market fund, biotechnology fund, or leveraged ETF can have substantial volatility.
Always examine what is actually inside the investment.
Risk Management Strategies for Stock Investors
1. Build an Emergency Fund First
Investing money that you may need to cover an unexpected expense can create unnecessary pressure.
An emergency fund can reduce the likelihood that you will be forced to sell investments during a market decline.
2. Diversify Across Companies and Sectors
Avoid allowing one company or one industry to dominate your portfolio unless you deliberately accept that level of concentration.
3. Diversify Across Asset Classes
Stocks do not have to represent 100% of your financial assets.
Depending on your objectives and risk profile, a portfolio may also include bonds, cash equivalents, or other asset classes.
4. Understand What You Own
Do not buy a stock merely because it is trending online.
Understand how the company makes money, what drives its earnings, how much debt it has, and what could cause the investment thesis to fail.
5. Avoid Excessive Leverage
Buying stocks with borrowed money can amplify both gains and losses.
A modest decline in the stock can become a much larger loss relative to your own capital when leverage is involved.
6. Match Investments to Your Time Horizon
Money needed in the next few months should generally not be exposed to the same level of market volatility as money intended for retirement decades from now.
7. Rebalance Periodically
A portfolio can become more concentrated simply because one investment rises faster than everything else.
Periodic rebalancing can help keep your portfolio aligned with its intended risk level.
8. Consider Dollar-Cost Averaging
Investing equal amounts at regular intervals can reduce the temptation to make a single large timing decision.
Dollar-cost averaging does not guarantee profits or eliminate losses, but it can provide a disciplined framework for investors who are adding money over time.
FINRA notes that periodic investing can help investors remain focused on long-term objectives during volatile markets.
A Practical Risk-Management Example
Consider two hypothetical investors, Alex and Jordan.
Alex
Alex has $100,000 and invests $70,000 in one technology company because he believes its artificial intelligence business will dominate the market.
The company subsequently misses earnings expectations and loses several major customers.
The stock falls 40%.
Alex’s portfolio loses approximately $28,000 from that one position alone.
Jordan
Jordan also has $100,000 but allocates the majority of the portfolio across a diversified mix of investments and keeps individual stock positions relatively small.
The same company falls 40%, but Jordan has only $5,000 invested in it.
The loss from that position is approximately $2,000.
Jordan’s portfolio can still decline if the broader market falls.
But the failure of one company is less likely to derail the entire financial plan.
The lesson is not that Jordan’s portfolio cannot lose money.
The lesson is that portfolio construction determines how much damage one mistake can cause.
What Stock Investors Should Monitor
A simple risk dashboard can help investors identify growing risks before they become serious problems.
| Metric | Why It Matters |
|---|---|
| Portfolio concentration | Shows dependence on individual positions |
| Sector exposure | Identifies industry concentration |
| Geographic exposure | Measures dependence on specific markets |
| Debt levels | Indicates financial leverage |
| Free cash flow | Shows the company’s ability to generate cash |
| Valuation multiples | Helps assess expectations embedded in price |
| Profit margins | Shows business profitability |
| Liquidity | Indicates how easily positions can be sold |
| Time horizon | Determines how much volatility you can realistically tolerate |
Five Questions to Ask Before Buying a Stock
1. What makes this company valuable?
If you cannot explain how the company generates revenue and profits, you may not understand the investment well enough.
2. What could make my investment thesis wrong?
Strong investors actively look for evidence that could disprove their assumptions.
3. What am I paying for the company?
A great company can still be overpriced.
4. How much of my portfolio will this investment represent?
A high-quality investment can become a high-risk position if it becomes too large relative to your overall portfolio.
5. What would I do if the stock fell 30%?
If the answer is “I would panic and sell,” your position may already be too large for your risk tolerance.
Common Mistakes That Increase Stock Investment Risk
Putting Too Much Money Into One Stock
High conviction can easily become excessive concentration.
Investing Without an Emergency Fund
A sudden financial emergency can force you to sell investments at an unfavorable time.
Using Margin Without Understanding the Consequences
Leverage magnifies losses as well as gains and can create forced selling.
Chasing Past Performance
A stock that has doubled is not necessarily safer simply because it has performed well.
Ignoring Valuation
Strong businesses can become expensive investments when expectations become unrealistic.
Confusing Diversification With Owning Many Tickers
Twenty investments can still have significant overlap if they depend on the same companies, sectors, or economic factors.
Checking the Portfolio Every Five Minutes
Constant monitoring can increase emotional reactions and encourage unnecessary trading.
Trying to Predict Every Market Move
Short-term market movements are extremely difficult to predict consistently.
Our guide on FOMO in investing explains why emotional reactions to market movements can be so damaging.
Should You Avoid Stocks Because They Are Risky?
Not necessarily.
The existence of risk does not mean an investment should automatically be avoided.
Stocks carry risk partly because investors expect compensation for taking that risk.
The challenge is determining whether the level of risk is appropriate for your financial situation.
For someone with a 30-year retirement horizon, a diversified allocation to equities may play an important role in long-term wealth building.
For someone who needs a down payment in three months, putting the entire amount into stocks may be inappropriate regardless of how attractive the expected return appears.
The investment itself cannot be evaluated separately from the investor.
Stock Investment Risk: A Simple Decision Framework
| Question | If Your Answer Is… | Potential Implication |
|---|---|---|
| When do I need the money? | Very soon | Be cautious with high-volatility assets |
| How diversified is my portfolio? | Very concentrated | Consider concentration risk |
| Can I tolerate a 30% decline? | No | Your equity exposure may be too aggressive |
| Do I understand the company? | No | Research before investing |
| Is the valuation reasonable? | Unclear | Investigate expectations and fundamentals |
| Do I have emergency savings? | No | Consider building financial resilience first |
| Am I investing because of FOMO? | Yes | Pause before making the investment |
Frequently Asked Questions
1. What is the biggest risk of investing in stocks?
There is no single biggest risk for every investor. For an individual stock, company-specific risk and concentration can be particularly significant. For a diversified portfolio, broad market risk may be the dominant risk.
2. Can I lose all my money in stocks?
Yes. An individual company’s stock can potentially fall to zero, particularly if the company becomes insolvent and common shareholders receive nothing after creditors and other claims are paid. A diversified portfolio makes a total loss much less likely, but does not eliminate losses.
3. Are stocks riskier than bonds?
Generally, stocks have greater price volatility and market risk than high-quality bonds, although the risk profile varies by specific investment. Bonds also carry risks such as credit, interest-rate, inflation, and liquidity risk.
4. Does diversification eliminate stock market risk?
No. Diversification can reduce company-specific and concentration risk, but a diversified stock portfolio can still decline substantially during a broad market downturn.
5. How many stocks should I own to be diversified?
There is no universal number. Diversification depends on the number of holdings as well as their industries, company sizes, geographies, and correlations. A portfolio of several companies from the same industry may remain highly concentrated.
6. Are index funds safer than individual stocks?
A broad index fund generally reduces company-specific risk because it owns many securities. However, it remains exposed to market risk and can decline significantly when the underlying market falls.
7. Can a stock be risky even if the company is profitable?
Yes. A profitable company can still have an expensive valuation, high debt, slowing growth, regulatory problems, or other risks that can cause its stock price to decline.
8. Why does valuation matter?
Because the price you pay determines the return you can potentially earn. If a stock price already assumes exceptionally strong future growth, even a good company can disappoint investors if results fall short of expectations.
9. Is stock market volatility the same as permanent loss?
No. Volatility describes fluctuations in market value. Permanent loss can occur when the underlying business deteriorates, an investor sells at a loss, or the investment fails to recover.
10. Is long-term stock investing risk-free?
No. A long investment horizon can help investors tolerate short-term volatility, but stocks remain risky assets even over long periods.
11. What is concentration risk?
Concentration risk is the possibility of suffering amplified losses because too much of your portfolio depends on one investment, company, sector, geography, or other correlated exposure.
12. How can I reduce stock investment risk?
Common risk-management approaches include diversification, appropriate asset allocation, maintaining emergency savings, limiting excessive concentration, avoiding unnecessary leverage, understanding investments before buying them, and matching investments to your time horizon.
13. Should I sell stocks when the market crashes?
Not automatically. The appropriate response depends on your financial plan, time horizon, liquidity needs, portfolio allocation, and the reason for the market decline. Selling solely because prices have fallen can turn temporary volatility into a permanent loss.
14. Does owning ETFs eliminate stock risk?
No. ETFs are investment vehicles, not guarantees of safety. A broad-market ETF can reduce company-specific risk, while a concentrated sector or leveraged ETF can carry substantial risk.
15. What is liquidity risk?
Liquidity risk is the possibility that you cannot sell an investment quickly at a reasonable price. It can become particularly important in thinly traded securities and during periods of market stress.
16. Can inflation hurt stock investors?
Yes. Inflation can reduce purchasing power and affect corporate costs, consumer demand, interest rates, and valuation multiples. Its effect varies considerably between companies and industries.
17. What is behavioral risk?
Behavioral risk is the risk that emotions such as fear, greed, overconfidence, or FOMO cause an investor to make decisions that undermine a sound long-term strategy.
18. Should beginners avoid individual stocks?
Not necessarily, but beginners should recognize that individual stocks require more research and create greater company-specific risk than broadly diversified funds. Starting with a diversified approach may be easier for investors who are still developing their investment knowledge.
19. How much of my portfolio should be in one stock?
There is no universal percentage that is appropriate for everyone. The answer depends on your risk tolerance, financial situation, other holdings, employment exposure, and investment strategy. The key is understanding how much damage the position could cause if it declined sharply.
20. What is the most important rule in stock investing?
Understand the risk before focusing on the potential return. A strong investment process considers what can go wrong, how much you could lose, and whether you can financially and emotionally withstand that outcome.
Final Thoughts
Stock investing can be an effective way to participate in economic growth and build long-term wealth, but it is never risk-free.
The risks go far beyond the simple possibility that “the stock price might fall.”
Investors need to think about:
- Market risk
- Company-specific risk
- Concentration risk
- Valuation risk
- Volatility
- Liquidity
- Interest rates
- Inflation
- Currency movements
- Behavioral mistakes
- Time horizon
The goal of successful risk management is not to eliminate all risk.
That is impossible.
The goal is to take risks that are appropriate for your financial situation while avoiding risks that can permanently derail your financial plan.
A diversified portfolio, adequate liquidity, realistic expectations, disciplined investing, and a long-term perspective can help investors manage the risks that come with owning stocks.
Ultimately, the best investor is not the person who takes no risk.
It is the person who understands which risks they are taking, why they are taking them, how much they can afford to lose, and whether their financial plan can survive the inevitable periods of market stress.
Pingback: 50 Best Performing S&P 500 Stocks in 2026: Top 50 YTD Gainers (As of November 6) - Daily Stock Markets