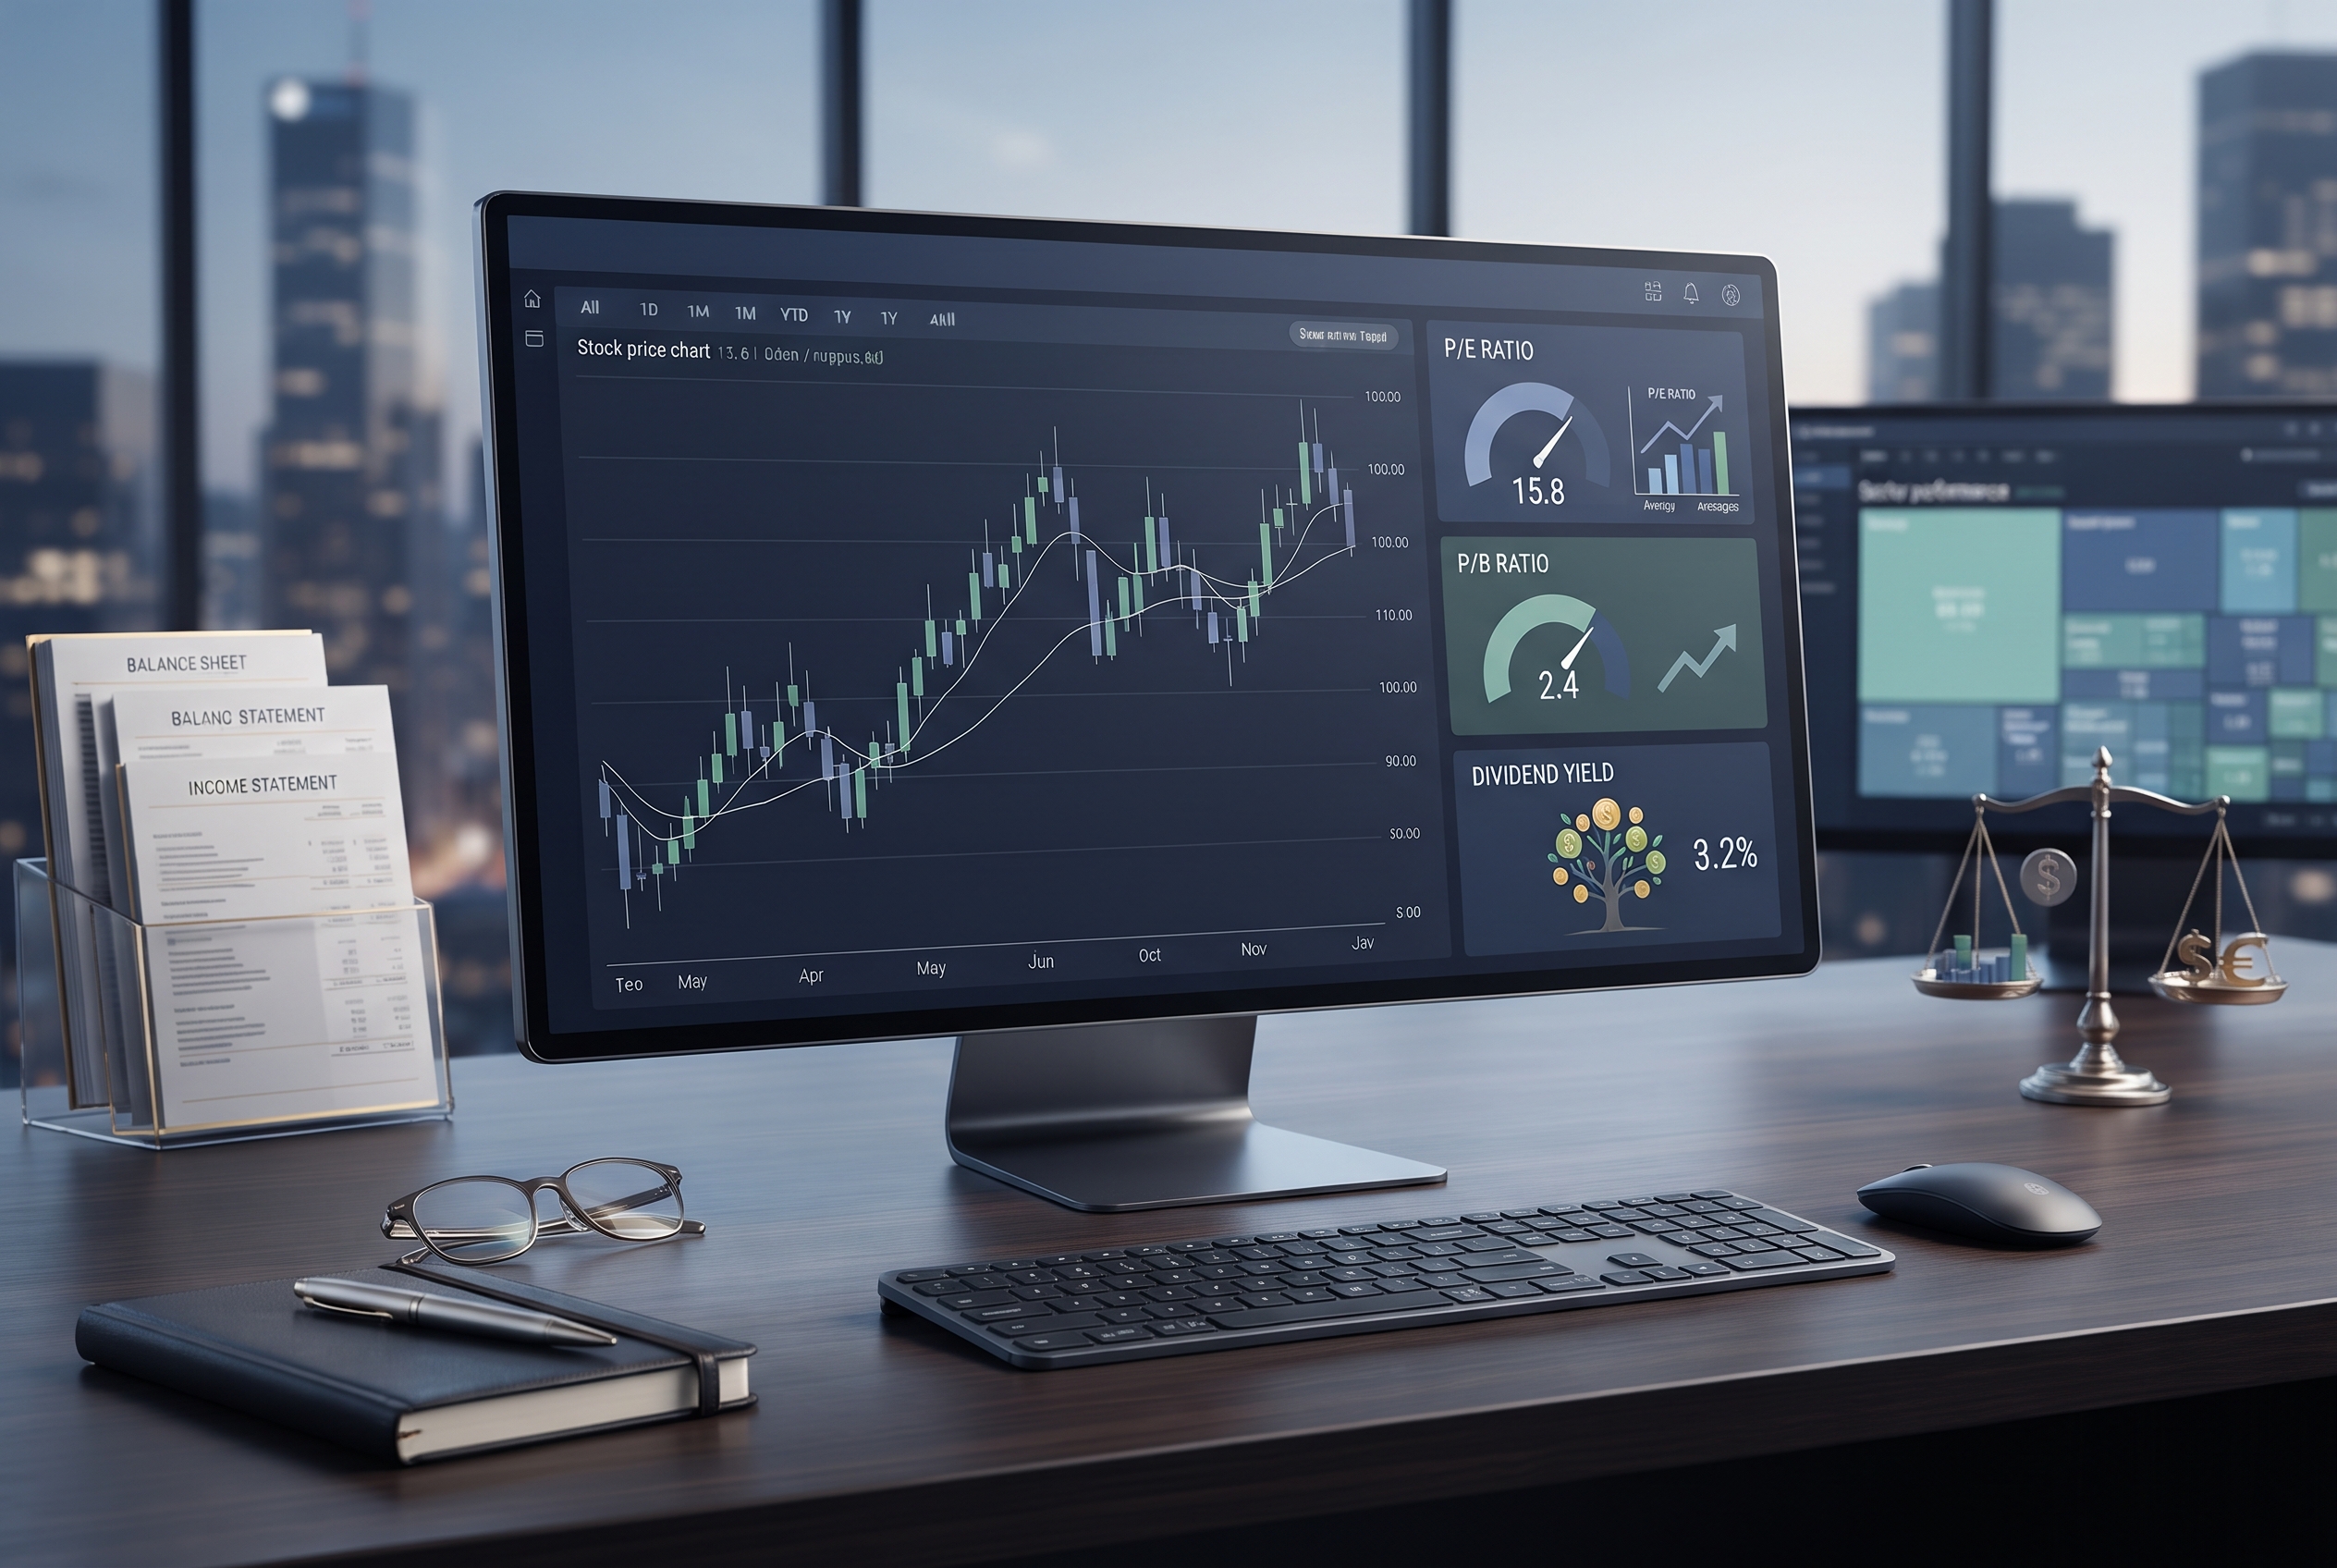
P/E Ratio, P/B Ratio, and Dividend Yield: What Do These Stock Market Metrics Really Tell You?
When evaluating a stock, investors often encounter a long list of financial ratios. Some of the most widely used are the price-to-earnings (P/E) ratio, the price-to-book (P/B) ratio, and dividend yield. These metrics may look complicated at first, but each answers a relatively straightforward question:
- P/E ratio: How much are investors paying for each dollar of a company’s earnings?
- P/B ratio: How does the market value a company compared with its accounting equity?
- Dividend yield: How much annual dividend income does a stock generate relative to its current share price?
These ratios can help investors compare companies, identify potential valuation discrepancies, and understand how a business rewards shareholders. However, none of them should be interpreted in isolation. A low P/E ratio does not automatically mean a stock is undervalued, a low P/B ratio does not guarantee hidden value, and a high dividend yield does not necessarily indicate a sustainable income opportunity.
This guide explains how these three important stock market ratios work, how to calculate them, what they reveal about a business, and how to combine them when analyzing investment opportunities.
30-Second Summary
- P/E ratio: Measures a stock’s price relative to its earnings per share. It helps investors understand how much the market is willing to pay for a company’s profitability.
- P/B ratio: Compares a company’s market price with its accounting book value. It is particularly useful when analyzing asset-heavy businesses and financial institutions.
- Dividend yield: Measures annual dividend payments as a percentage of the current share price. It helps income-focused investors evaluate potential cash distributions.
- Context matters: Ratios should be compared with industry peers, historical levels, earnings quality, financial strength, and future prospects.
- Use multiple metrics: A more reliable assessment combines valuation ratios with profitability, cash flow, debt, and business fundamentals.
1. What Are Financial Ratios in Stock Analysis?
Financial ratios are calculations that transform information from a company’s financial statements and market data into indicators that investors can interpret more easily.
A company’s annual report may contain hundreds of pages of financial information. Revenue, operating expenses, net income, total assets, liabilities, shareholders’ equity, and cash flow all provide useful information. However, looking at these figures individually may not reveal whether the company’s stock is attractively valued.
Financial ratios help connect the company’s financial performance with its market valuation.
For example, imagine two companies that each generate $1 billion in annual net income. Company A has a market capitalization of $10 billion, while Company B has a market capitalization of $25 billion.
Although their reported profits are identical, investors are paying different amounts for those earnings. A valuation ratio helps make this difference visible.
Financial ratios are useful for several reasons:
- Comparing companies operating in the same industry.
- Evaluating whether a stock appears expensive or inexpensive relative to its fundamentals.
- Understanding how effectively a company generates profits.
- Assessing the potential income available to shareholders.
- Tracking changes in a company’s valuation over time.
- Identifying areas that deserve further financial investigation.
Three of the most familiar metrics are the price-to-earnings ratio, price-to-book ratio, and dividend yield. Let’s examine each one in detail.
2. What Is the Price-to-Earnings (P/E) Ratio?
The price-to-earnings ratio (P/E) measures the relationship between a company’s stock price and its earnings per share (EPS). It indicates how much investors are willing to pay for each dollar of earnings generated by the company.
In simple terms, the P/E ratio answers this question: How many dollars does the market currently assign to every dollar of annual earnings per share?
How to Calculate the P/E Ratio
The formula is:
P/E Ratio = Current Share Price / Earnings Per Share (EPS)
EPS represents the portion of a company’s profit attributable to each outstanding common share. It is generally calculated using net income available to common shareholders divided by the weighted-average number of diluted or basic shares, depending on the EPS measure being used.
P/E Ratio Example
Suppose a fictional company, Northstar Technologies, has the following financial figures:
- Current share price: $60
- Annual earnings per share: $4
Its P/E ratio is:
$60 / $4 = 15
This means investors are paying $15 for every $1 of annual earnings per share.
Now imagine another company in the same industry has a share price of $90 and EPS of $3. Its P/E ratio would be:
$90 / $3 = 30
The second company has a P/E ratio twice as high as the first. That does not automatically mean it is overvalued. Investors may expect stronger future earnings growth, a more competitive business model, or more predictable profits.
What Does a Low P/E Ratio Mean?
A relatively low P/E ratio may indicate that a stock is inexpensive compared with its current earnings. However, investors should investigate why the market is assigning a lower valuation.
Possible explanations include:
- The company is experiencing declining revenue or profitability.
- Its industry is facing structural challenges.
- The business has significant debt or financial risks.
- Investors expect earnings to fall in the future.
- The company faces regulatory, competitive, or operational uncertainty.
- The stock may genuinely be undervalued relative to its long-term prospects.
A low P/E ratio can therefore represent either an investment opportunity or a warning sign. The difference depends on the quality and sustainability of the company’s earnings.
What Does a High P/E Ratio Mean?
A high P/E ratio means investors are paying a relatively large amount for each dollar of current earnings.
This can happen when a company has:
- Strong expected earnings growth.
- A competitive advantage or valuable intellectual property.
- A scalable business model.
- Consistent revenue growth.
- High profit margins.
- Strong investor confidence.
For example, a fast-growing software company may trade at a higher P/E ratio than a mature industrial company because investors expect its earnings to expand rapidly.
However, high expectations create risk. If the company fails to deliver the growth investors anticipate, its valuation may contract even if earnings continue to increase.
Trailing P/E vs. Forward P/E
Investors should understand the difference between trailing and forward P/E ratios.
| Metric | Calculation | What It Shows |
|---|---|---|
| Trailing P/E | Share price / earnings per share over the previous 12 months | Valuation based on reported historical earnings |
| Forward P/E | Share price / estimated earnings per share for a future period | Valuation based on analysts’ earnings expectations |
Trailing P/E uses reported financial results, while forward P/E relies on forecasts. Forward earnings estimates can change as business conditions evolve, so they should not be treated as guaranteed outcomes.
When Is the P/E Ratio Most Useful?
The P/E ratio is generally more meaningful when comparing profitable companies with reasonably stable earnings.
It is commonly used when analyzing:
- Established consumer companies.
- Industrial businesses.
- Large-cap technology companies with positive earnings.
- Healthcare companies with established profitability.
- Companies with relatively predictable earnings patterns.
It becomes less useful when a company reports negative earnings, experiences unusually volatile profits, or has earnings distorted by one-time events.
3. What Is the Price-to-Book (P/B) Ratio?
The price-to-book ratio (P/B) compares a company’s market value with its accounting book value. It shows how much investors are paying for each dollar of shareholders’ equity recorded on the balance sheet.
While the P/E ratio focuses on earnings, the P/B ratio focuses on the company’s net assets as represented by its accounting equity.
How to Calculate the P/B Ratio
There are two commonly used versions of the formula:
P/B Ratio = Market Capitalization / Total Shareholders’ Equity
Or, on a per-share basis:
P/B Ratio = Share Price / Book Value Per Share
Book value is generally calculated as total assets minus total liabilities. When calculating book value attributable to common shareholders, preferred equity and other relevant claims may need to be deducted.
What Is Book Value Per Share?
Book value per share (BVPS) estimates the accounting equity attributable to each common share.
A simplified formula is:
Book Value Per Share = Common Shareholders’ Equity / Common Shares Outstanding
For example, suppose a company has:
- Total shareholders’ equity attributable to common shareholders: $5 billion
- Common shares outstanding: 500 million
Its book value per share is:
$5 billion / 500 million = $10
If its stock trades at $20, its P/B ratio is:
$20 / $10 = 2.0
The market is valuing the company at twice its accounting book value.
What Does a P/B Ratio Below 1 Mean?
A P/B ratio below 1 means the company’s market capitalization is lower than its reported book equity.
At first glance, this may appear attractive. Investors are effectively paying less than one dollar for each dollar of accounting equity.
However, a low P/B ratio can reflect legitimate concerns:
- The company’s assets may be overvalued or difficult to sell.
- The business may be generating poor returns on equity.
- Its industry may be experiencing long-term decline.
- The company may have substantial financial or operational risks.
- Investors may expect future losses or asset impairments.
In some situations, a P/B ratio below 1 may identify a potentially undervalued company. In others, it may reflect a business whose assets are not generating attractive returns.
What Does a P/B Ratio Above 1 Mean?
A P/B ratio above 1 means the market values the company at more than its accounting equity.
This may reflect expectations of:
- Strong future profitability.
- High returns on shareholders’ equity.
- Valuable brands and intellectual property.
- Intangible assets that are not fully represented on the balance sheet.
- Competitive advantages and growth opportunities.
A high P/B ratio is not necessarily a sign of overvaluation. A company that consistently generates strong returns on equity may deserve to trade at a premium to its book value.
Which Industries Are Best Suited to P/B Analysis?
The P/B ratio is often particularly relevant when analyzing businesses whose assets and liabilities are central to their operations.
Examples include:
- Banks.
- Insurance companies.
- Other financial institutions.
- Asset-intensive industrial businesses.
- Some real estate companies.
It is generally less informative for companies whose value depends heavily on internally developed software, brands, research capabilities, and other intangible assets.
For example, a technology company may have substantial economic value in its software platform, customer relationships, and intellectual property. Much of this value may not appear as an equivalent asset on its balance sheet.
4. What Is Dividend Yield?
Dividend yield measures the annual dividend income a company distributes relative to its current share price. It is expressed as a percentage.
For investors seeking regular cash income from their portfolios, dividend yield is an important metric.
How to Calculate Dividend Yield
The basic formula is:
Dividend Yield = Annual Dividend Per Share / Current Share Price × 100
Annual dividend per share generally represents the total dividends paid over the previous 12 months or an annualized estimate based on the current declared dividend. Investors should distinguish historical payments from forward dividend estimates.
Dividend Yield Example
Suppose a fictional company, Harbor Utilities, pays $2 in dividends per share annually. Its stock currently trades at $40.
The calculation is:
($2 / $40) × 100 = 5%
The stock has a dividend yield of 5% based on the stated annual dividend and current share price.
An investor holding 100 shares would receive $200 in annual dividends if the company maintains that payment and the investor remains eligible for the distributions.
Dividend payments are not guaranteed. A company’s board may increase, reduce, suspend, or eliminate dividends depending on its financial position and business priorities.
What Does a High Dividend Yield Mean?
A high dividend yield may be attractive to investors who prioritize income. It can indicate that a company distributes a relatively large amount of cash compared with its share price.
Companies with established operations and relatively predictable cash flows may be more likely to distribute regular dividends.
However, an unusually high yield deserves closer examination.
One reason is that dividend yield moves inversely with the share price, assuming the dividend remains unchanged.
For example:
- Annual dividend per share: $4
- Previous share price: $100
- Previous dividend yield: 4%
- New share price: $60
- New dividend yield: 6.67%
The yield has increased from 4% to approximately 6.67%, even though the company has not raised its dividend. The increase is entirely due to the falling share price.
If the stock price declined because investors expect weaker earnings or a dividend reduction, the higher yield could be misleading.
What Is a Dividend Yield Trap?
A dividend yield trap occurs when a stock appears attractive because of its high dividend yield, but the underlying business may not be able to sustain its dividend payments.
Warning signs can include:
- Declining operating cash flow.
- Repeated increases in debt to finance dividend payments.
- A payout ratio that is too high relative to sustainable earnings.
- Falling revenue and profitability.
- Significant refinancing requirements.
- A business facing structural industry challenges.
Investors should therefore examine the company’s dividend payout ratio, free cash flow, debt levels, and earnings stability before relying on dividend yield.
What Is the Dividend Payout Ratio?
The dividend payout ratio measures the proportion of earnings distributed to shareholders as dividends.
Dividend Payout Ratio = Dividends Per Share / Earnings Per Share × 100
For example, if a company earns $5 per share and pays $2 per share in annual dividends, its payout ratio is:
($2 / $5) × 100 = 40%
This means the company distributes 40% of its earnings as dividends and retains the remaining 60% for other purposes, such as reinvestment, debt reduction, or cash reserves.
A payout ratio should be evaluated in the context of the company’s industry, cash flow, capital requirements, and dividend policy. Some businesses can sustain higher payout ratios than others.
5. P/E vs. P/B vs. Dividend Yield: Key Differences
Although these three ratios are often discussed together, they measure different aspects of a company’s financial and market profile.
| Metric | What It Measures | Formula | Most Useful For |
|---|---|---|---|
| P/E Ratio | Market price relative to earnings | Share Price / EPS | Evaluating profitable companies |
| P/B Ratio | Market price relative to accounting equity | Share Price / Book Value Per Share | Analyzing banks and asset-heavy businesses |
| Dividend Yield | Annual dividend income relative to share price | Annual Dividend Per Share / Share Price × 100 | Evaluating dividend income potential |
Consider three hypothetical companies:
| Company | P/E | P/B | Dividend Yield |
|---|---|---|---|
| GrowthTech | 32 | 5.2 | 0.3% |
| ValueIndustries | 12 | 0.9 | 3.5% |
| StableBank | 10 | 1.1 | 4.2% |
These figures suggest different investment profiles:
- GrowthTech: The market assigns a relatively high valuation, potentially reflecting expectations of future growth. Its dividend contribution is limited.
- ValueIndustries: The company trades at lower earnings and book-value multiples and offers a moderate dividend yield. Further analysis is needed to determine whether the valuation reflects an opportunity or business risks.
- StableBank: Its relatively low P/E and moderate P/B may be worth examining alongside capital adequacy, credit quality, loan growth, and profitability.
None of these profiles is automatically superior. The right interpretation depends on the business model, financial condition, valuation history, and the investor’s objectives.
6. How to Use These Ratios Together When Evaluating a Stock
One of the most common mistakes in stock analysis is relying on a single financial ratio. A more useful approach is to combine several indicators and examine whether they support the same conclusion.
Step 1: Examine Earnings and the P/E Ratio
Start by reviewing the company’s earnings history and current P/E ratio.
Ask the following questions:
- Is the company consistently profitable?
- Are earnings growing or declining?
- Is its P/E ratio higher or lower than comparable companies?
- Are current earnings affected by unusual one-time items?
- Does the valuation appear reasonable given future growth expectations?
Step 2: Review the P/B Ratio and Balance Sheet
Next, examine the company’s assets, liabilities, and shareholders’ equity.
Look at whether the company’s book value is growing, whether its assets are productive, and whether debt levels are manageable.
For banks and insurers, book value can be particularly relevant, but investors should also investigate asset quality, capital requirements, and potential credit losses.
Step 3: Assess Dividend Sustainability
If the company pays dividends, calculate its dividend yield and payout ratio.
Then examine:
- Whether dividends have been consistent over time.
- Whether operating cash flow supports the payments.
- Whether the payout ratio is sustainable.
- Whether the company has significant upcoming capital expenditure requirements.
- Whether management has communicated a clear dividend policy.
Step 4: Compare the Company With Industry Peers
A valuation ratio becomes more informative when compared with companies operating under similar economic conditions.
Comparing a bank with a software company, for example, may produce misleading conclusions because their capital structures, asset bases, growth opportunities, and profitability profiles are fundamentally different.
Instead, compare companies with similar:
- Business models.
- Revenue sources.
- Growth rates.
- Profit margins.
- Debt levels.
- Capital requirements.
Step 5: Look Beyond the Three Ratios
P/E, P/B, and dividend yield provide useful starting points, but they do not tell the complete story.
Consider adding the following metrics:
| Additional Metric | What It Helps Evaluate |
|---|---|
| EPS Growth | Whether earnings are expanding over time |
| Return on Equity (ROE) | How effectively a company generates profit from shareholders’ equity |
| Debt-to-Equity Ratio | The relationship between debt financing and equity |
| Free Cash Flow | Cash remaining after operating and capital expenditure requirements |
| Operating Margin | How efficiently the company converts revenue into operating profit |
| PEG Ratio | How the P/E ratio relates to expected earnings growth |
For a more detailed look at company valuation, read our guide on how to use fundamental analysis to choose stocks.
7. A Practical Example: Evaluating Three Stocks
Imagine an investor named Alex is comparing three fictional companies listed on a US stock exchange. Alex wants to understand their valuations and dividend profiles before conducting further research.
The companies have the following figures:
| Metric | Company A | Company B | Company C |
|---|---|---|---|
| Share Price | $50 | $80 | $40 |
| EPS | $5 | $2.50 | $4 |
| Book Value Per Share | $25 | $20 | $50 |
| Annual Dividend Per Share | $1.50 | $0.80 | $2 |
| P/E Ratio | 10 | 32 | 10 |
| P/B Ratio | 2.0 | 4.0 | 0.8 |
| Dividend Yield | 3.0% | 1.0% | 5.0% |
Let’s interpret the results.
Company A: Moderate Valuation and Dividend Income
Company A has a P/E ratio of 10, a P/B ratio of 2, and a dividend yield of 3%.
Its valuation relative to earnings is lower than Company B’s, while its dividend yield is higher. Alex may want to investigate whether the company’s earnings are stable and whether its dividend is supported by cash flow.
Company B: Higher Growth Expectations May Be Priced In
Company B has a P/E ratio of 32 and a P/B ratio of 4. Its dividend yield is only 1%.
The market may be assigning a premium because of expected growth, profitability, or competitive advantages. Alex should examine whether the company’s future earnings potential justifies its valuation.
Company C: Low P/B and High Dividend Yield
Company C has a P/B ratio of 0.8 and a dividend yield of 5%.
These figures may initially appear attractive. However, Alex should investigate why the market values the company below its book equity. The company could be facing declining asset quality, weak profitability, financial stress, or other challenges.
Alex should also determine whether the 5% dividend yield is sustainable. If earnings and cash flow are deteriorating, the company may eventually reduce its dividend.
The lesson: Financial ratios help investors identify questions worth investigating. They do not provide automatic buy or sell signals.
All companies and figures in this example are fictional and provided solely for educational purposes.
8. Common Mistakes Investors Make When Interpreting Financial Ratios
Even experienced investors can misinterpret financial ratios when they overlook the assumptions behind them.
Mistake 1: Assuming a Low P/E Always Means a Stock Is Cheap
A low P/E ratio may reflect declining earnings, weak future prospects, or significant business risks. Investors should examine the sustainability of profits before drawing conclusions.
Mistake 2: Treating a High P/E as Proof of Overvaluation
A company with strong growth prospects and high-quality earnings may reasonably trade at a premium. The key question is whether future performance can justify that valuation.
Mistake 3: Assuming a P/B Below 1 Guarantees Undervaluation
Accounting book value does not necessarily represent the amount shareholders could recover if a company were liquidated. Asset quality, liabilities, and business risks matter.
Mistake 4: Chasing the Highest Dividend Yield
An unusually high yield may result from a falling stock price. Investors should evaluate dividend sustainability rather than focusing exclusively on the percentage.
Mistake 5: Comparing Companies From Different Industries
Different industries have different financial structures and economic characteristics. Comparisons are more meaningful among businesses with similar operations and capital requirements.
Mistake 6: Ignoring One-Time Earnings
A company may report unusually high profits because of an asset sale, tax benefit, or other non-recurring event. Such earnings can distort its P/E ratio.
Mistake 7: Using Outdated Financial Data
Stock prices change continuously, while financial statements are published periodically. Investors should make sure that the market price and financial data used in a calculation are sufficiently current and comparable.
Mistake 8: Forgetting That Ratios Reflect Different Accounting and Market Assumptions
Companies may report financial results under different accounting frameworks, and data providers may use different definitions of earnings, book value, or annualized dividends. Investors should understand what is included in each calculation.
9. How to Build a Better Stock Valuation Checklist
Before making an investment decision, investors can use a simple checklist to organize their research.
- Have I reviewed the company’s latest annual and quarterly financial statements?
- Is the company consistently profitable?
- Have I calculated or checked its trailing and forward P/E ratios?
- How does its P/E compare with industry peers and its own historical range?
- Is its P/B ratio meaningful for its business model?
- Are its assets and liabilities of good quality?
- Does the company generate sufficient operating cash flow?
- Is its dividend yield supported by earnings and cash flow?
- Is the dividend payout ratio sustainable?
- Have I considered debt, profitability, growth, and competitive risks?
- Do I understand why the market may be assigning the current valuation?
This process helps prevent investors from relying on a single attractive-looking number.
10. Final Thoughts: Ratios Are Tools, Not Investment Decisions
The P/E ratio, P/B ratio, and dividend yield are among the most widely used metrics in stock analysis. Each offers a different perspective on a company’s financial profile.
The P/E ratio connects the share price with earnings. The P/B ratio compares market value with accounting equity. Dividend yield shows the relationship between annual shareholder distributions and the current stock price.
Used together, these indicators can help investors understand how the market values a business, how its financial position compares with peers, and whether its dividend policy may support an income-oriented strategy.
But numbers need context. A company with a low P/E may have deteriorating fundamentals. A company with a high P/B may possess valuable intangible assets and strong profitability. A stock with an impressive dividend yield may be facing a dividend cut.
The most effective approach is to combine valuation ratios with financial statement analysis, cash flow assessment, industry comparisons, and an understanding of the company’s long-term competitive position.
Ultimately, successful stock analysis is not about finding the lowest ratio or the highest yield. It is about understanding what the numbers reveal—and what they leave out.
Frequently Asked Questions (FAQs)
1. What is the P/E ratio in simple terms?
The P/E ratio shows how much investors are paying for each dollar of a company’s earnings per share. It is calculated by dividing the current stock price by earnings per share.
2. What is considered a good P/E ratio?
There is no universal ideal P/E ratio. A reasonable valuation depends on the company’s industry, earnings growth, profitability, risk profile, and historical valuation. Comparisons with similar businesses are generally more useful than applying a single benchmark.
3. Is a low P/E ratio always better?
No. A low P/E may indicate an inexpensive stock, but it can also reflect declining earnings, financial difficulties, or weak future growth expectations.
4. What does a P/E ratio of 20 mean?
A P/E ratio of 20 means investors are paying $20 for each $1 of annual earnings per share, based on the earnings measure used in the calculation.
5. What is the difference between trailing P/E and forward P/E?
Trailing P/E uses earnings from the previous 12 months, while forward P/E uses estimated future earnings. Forward P/E depends on forecasts and may change as expectations evolve.
6. Can a company have a negative P/E ratio?
Yes. A company with negative earnings per share may have a negative calculated P/E. In practice, negative P/E ratios are generally not meaningful for conventional valuation comparisons.
7. What is the P/B ratio?
The price-to-book ratio compares a company’s market value with its accounting equity. It is calculated by dividing the share price by book value per share.
8. Is a P/B ratio below 1 good?
It can indicate that a stock trades below its accounting book value, but it does not guarantee undervaluation. Investors should investigate asset quality, profitability, liabilities, and the company’s future prospects.
9. Why is P/B useful for banks?
Banks have balance sheets that are central to their business models. Their loans, investments, deposits, and shareholders’ equity are important components of financial analysis. P/B can therefore provide a useful valuation reference, alongside measures such as return on equity and asset quality.
10. Is P/B useful for technology companies?
It can provide some information, but it may be less informative for businesses whose value comes largely from software, brands, intellectual property, and other intangible assets that may not be fully reflected in accounting book value.
11. What is dividend yield?
Dividend yield measures annual dividend payments per share relative to the current share price. It is usually expressed as a percentage.
12. How do you calculate dividend yield?
Divide the annual dividend per share by the current stock price and multiply the result by 100. For example, a $2 annual dividend on a $40 stock represents a 5% yield.
13. Is a higher dividend yield always better?
No. A high yield can be caused by a falling share price and may signal that investors expect the dividend to be reduced. Dividend sustainability is more important than the headline yield alone.
14. What is a dividend yield trap?
A dividend yield trap is a stock that appears attractive because of its high yield but may be unable to maintain its dividend payments due to weak earnings, poor cash flow, excessive debt, or deteriorating business conditions.
15. What is the dividend payout ratio?
The dividend payout ratio measures the proportion of earnings distributed as dividends. It is calculated by dividing dividends per share by earnings per share and multiplying by 100.
16. What is the difference between dividend yield and dividend payout ratio?
Dividend yield compares the annual dividend with the stock price, while the payout ratio compares dividends with company earnings. Yield focuses on shareholder income relative to market price; payout ratio focuses on how much profit the company distributes.
17. Can a company have a high dividend yield and a low P/E ratio?
Yes. A mature company with relatively low earnings valuation and substantial dividend distributions may have both characteristics. However, investors should determine whether its earnings and cash flow can support future payments.
18. Which ratio is most important when choosing stocks?
No single ratio is sufficient. P/E, P/B, and dividend yield answer different questions. The most useful combination depends on the company’s business model and the purpose of the analysis.
19. Should investors compare P/E and P/B ratios across different industries?
Cross-industry comparisons can be misleading because industries have different growth rates, asset structures, capital requirements, and profitability profiles. Comparing companies with similar business models is generally more informative.
20. Are P/E, P/B, and dividend yield enough to make an investment decision?
No. These ratios are useful starting points, but investors should also review financial statements, cash flow, debt, earnings quality, management, competitive position, and business risks. They should not be treated as standalone buy or sell signals.
Pingback: Intrinsic Value: What Is It and How Do You Calculate a Stock's True Worth? - Daily Stock Markets