Primary vs. Secondary Offerings: What Is the Difference and Why Does It Matter?
When a company offers shares to investors, one of the most important questions is where the shares come from and who receives the money.
Is the company issuing new shares to raise capital? Are existing shareholders selling shares they already own? Or does the transaction combine both?
These questions help investors understand the difference between primary and secondary offerings.
The distinction matters because the two structures have different effects on a company’s finances, ownership, share count, and future growth opportunities. A primary offering generally provides new capital to the company, while a secondary sale by existing shareholders provides liquidity to those shareholders.
However, the terminology can be confusing. In particular, a company’s initial public offering (IPO) may contain both newly issued shares and shares sold by existing shareholders. In addition, the term secondary offering is sometimes used to describe a public share sale conducted after a company has already listed.
This guide explains primary and secondary offerings, how they work, how they affect investors, and what to examine before participating in a stock offering.
30-Second Summary: Primary vs. Secondary Offerings
- Primary offering: A company issues new shares and sells them to investors. The company receives the proceeds and can use the capital to finance growth, acquisitions, working capital, or debt repayment.
- Secondary offering by existing shareholders: Existing shareholders sell shares they already own. The proceeds go to the selling shareholders, not the company.
- Combined offering: A transaction includes both newly issued shares and existing shares sold by current shareholders.
- Dilution: Issuing new shares increases the number of shares outstanding and can reduce existing shareholders’ ownership percentages.
- Non-dilutive shareholder sale: When existing shares change hands without creating new shares, the total share count does not increase.
- IPO vs. secondary offering: An IPO is a company’s first public offering. A secondary offering generally refers to a subsequent offering by an already-public company, although the term can also describe the secondary component of an IPO.
- Investor takeaway: Always check who is selling, where the proceeds go, how many new shares are being issued, and how the transaction affects ownership.
1. What Is a Primary Offering?
A primary offering occurs when a company issues new securities and sells them to investors.
In an equity offering, the company creates and sells additional shares. The proceeds are paid to the issuing company, generally after underwriting fees and other transaction expenses.
Companies use primary offerings to raise capital for business purposes.
These may include:
- Expanding into new markets
- Building production facilities
- Investing in research and development
- Developing new products and services
- Acquiring other businesses
- Reducing outstanding debt
- Financing day-to-day operations
- Strengthening the company’s balance sheet
A primary offering can take place when a private company conducts its first IPO or when an already-public company raises additional equity capital.
How Does a Primary Offering Work?
Consider a fictional U.S.-based technology company called TechNova.
TechNova wants to expand its cloud infrastructure and develop new software products. Management estimates that the company needs $100 million to finance its plans.
Instead of relying entirely on bank loans, TechNova decides to issue 5 million new shares at $20 per share.
The calculation is:
5 million shares × $20 = $100 million
TechNova receives $100 million in gross proceeds before offering expenses.
The company can then use the funds according to the objectives described in its offering documents.
Why Do Companies Choose Primary Offerings?
Access to growth capital: Companies can obtain equity financing to support expansion without taking on an equivalent amount of debt.
Debt reduction: Proceeds may be used to repay loans, reduce interest expenses, and improve financial flexibility.
Investment in innovation: Businesses can finance research, product development, technology infrastructure, and new capabilities.
Strategic acquisitions: Companies may use the capital to acquire competitors or businesses that complement their existing operations.
Balance sheet improvement: Raising equity can strengthen the company’s capital structure and reduce financial leverage.
What Should Investors Know?
A primary offering increases the number of shares outstanding.
This can dilute the ownership percentage of existing shareholders.
For example, suppose a company has 20 million shares outstanding and issues another 5 million shares.
Before the offering, an investor who owns 1 million shares has:
1 million ÷ 20 million = 5% ownership
After the offering, assuming all 5 million new shares are issued and no other share-count changes occur:
1 million ÷ 25 million = 4% ownership
The investor still owns 1 million shares, but the percentage ownership has decreased.
This is known as ownership dilution.
Dilution is not necessarily negative. If the company uses the new capital effectively and increases its earnings and business value, existing shareholders may benefit despite owning a smaller percentage of the company.
The key question is whether the capital raised can generate sufficient value to justify the additional shares.
2. What Is a Secondary Offering?
The term secondary offering can have more than one meaning in financial markets.
In the context of a share sale by existing shareholders, it refers to the sale of shares that have already been issued and are held by current investors.
Instead of the company issuing new shares, existing shareholders offer some of their holdings to other investors.
The proceeds generally go to the shareholders selling the shares rather than to the company.
This type of transaction is also commonly called a secondary share sale or a selling-shareholder offering.
How Does a Secondary Share Sale Work?
Imagine that an early investor owns 4 million shares in a publicly traded company.
The investor decides to sell 1 million shares at $30 each.
The gross proceeds are:
1 million shares × $30 = $30 million
The selling shareholder receives the $30 million before applicable transaction expenses and taxes.
The company does not receive this money.
Because the transaction involves existing shares rather than newly issued shares, the total number of shares outstanding does not increase as a result of the sale.
Ownership simply transfers from one shareholder to another.
Why Do Existing Shareholders Sell Their Shares?
There are several reasons why shareholders may decide to sell part of their holdings.
Realizing investment gains: Early investors may have supported a company for years and want to convert part of their investment into cash.
Portfolio diversification: Founders and major shareholders may have a significant portion of their wealth concentrated in one company. Selling shares can help reduce this concentration.
Fund distributions: Venture capital and private equity funds may sell holdings to generate proceeds for their own investors.
Changing investment priorities: Institutional investors may adjust their portfolios based on market conditions, risk exposure, or investment strategy.
Providing liquidity: Existing shareholders may want to reduce their holdings while retaining a meaningful ownership stake.
Does a Secondary Share Sale Mean That Insiders Have Lost Confidence?
Not necessarily.
A shareholder selling shares does not automatically indicate that the company is performing poorly or that management expects the stock price to decline.
The reasons behind the sale matter.
For example, an early-stage investor may have held shares for eight years and decide to sell a portion to distribute gains to its fund investors.
That decision may be related to the fund’s investment lifecycle rather than the company’s business outlook.
Nevertheless, investors should examine:
- Who is selling the shares?
- How many shares are being sold?
- What percentage of the shareholder’s existing stake is being sold?
- Will the shareholder retain a significant ownership position?
- Are founders and senior executives also selling?
- What is the company’s current financial and operational performance?
The context is more important than the simple fact that a shareholder is selling.
3. Primary vs. Secondary Offerings: Key Differences
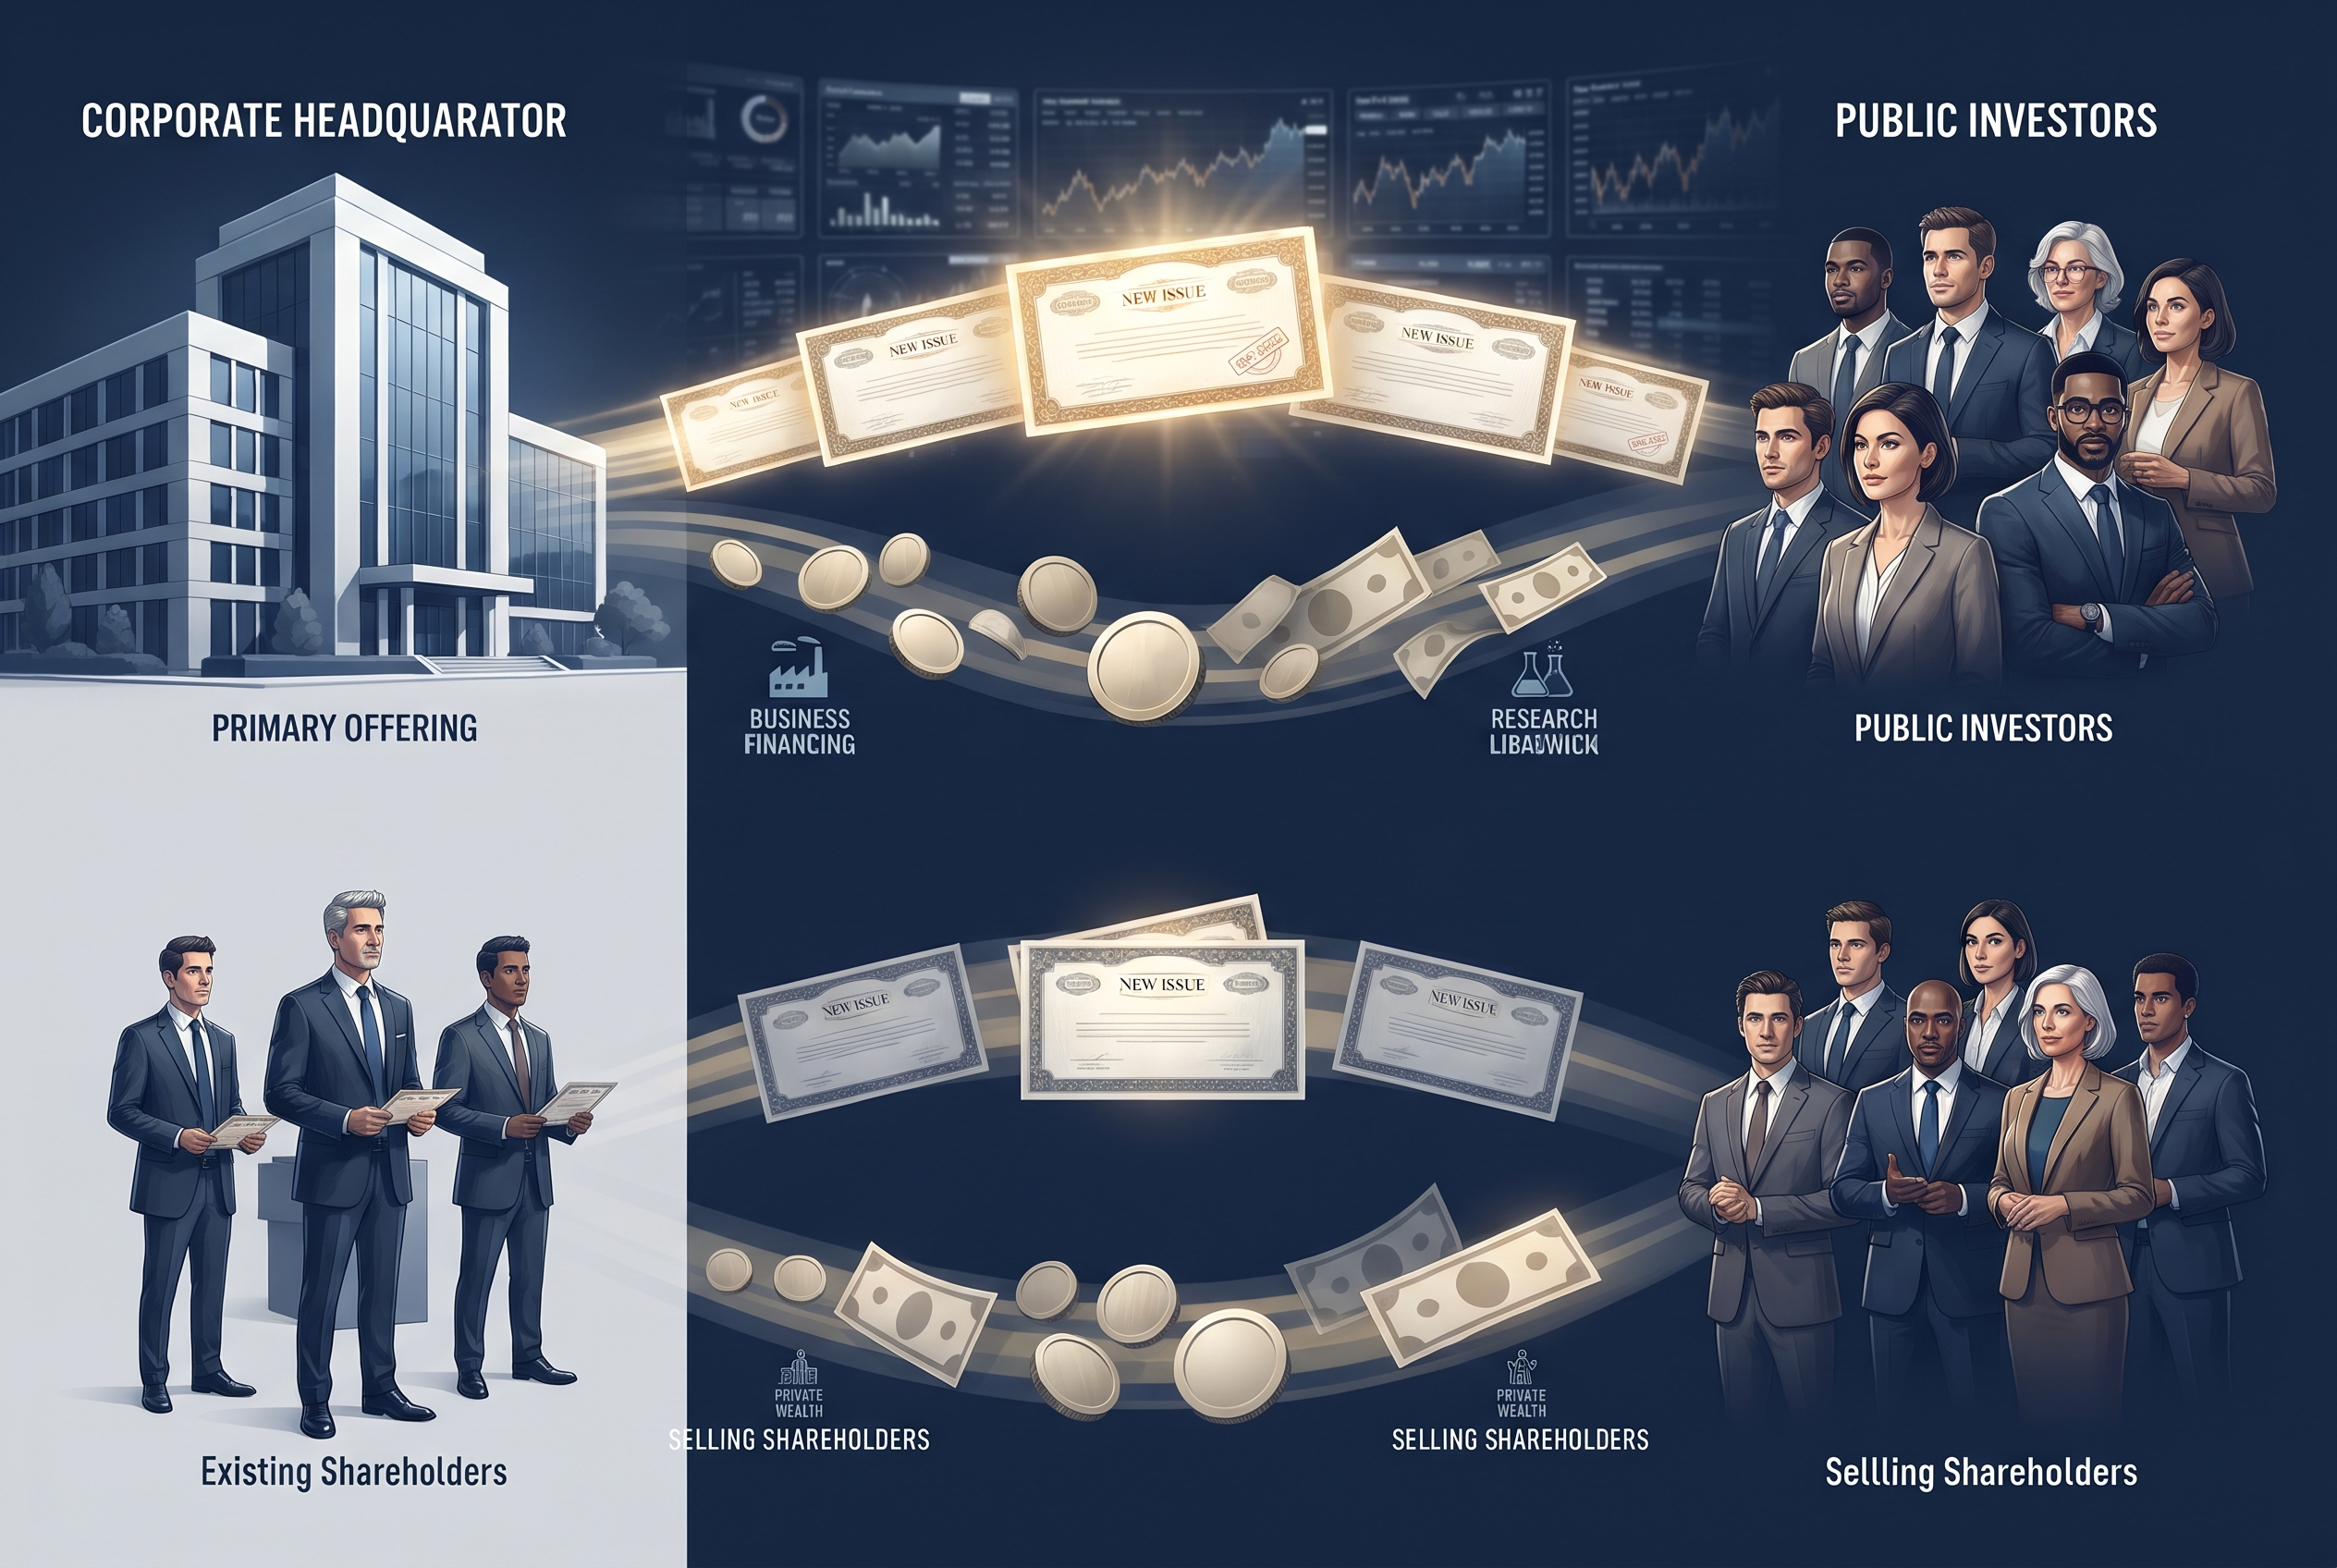
The main difference between a primary offering and a secondary share sale is who sells the shares and who receives the proceeds.
| Feature | Primary Offering | Secondary Share Sale |
|---|---|---|
| Who sells the shares? | The company | Existing shareholders |
| Are new shares issued? | Yes | No |
| Who receives the proceeds? | The company | Selling shareholders |
| Does the share count increase? | Generally yes | No, as a result of the sale itself |
| Does it create ownership dilution? | Generally yes | No, not from the transfer itself |
| Main purpose | Raising capital for the company | Providing liquidity to existing shareholders |
| Potential use of proceeds | Expansion, acquisitions, debt repayment, working capital | Personal, institutional, or fund-related financial objectives |
A Simple Way to Remember the Difference
Think about the transaction from the company’s perspective.
In a primary offering:
- The company creates new shares.
- Investors purchase those shares.
- The company receives the proceeds.
- The total number of shares outstanding increases.
In a secondary share sale:
- Existing shareholders sell shares they already own.
- New investors purchase those shares.
- Selling shareholders receive the proceeds.
- The total number of shares outstanding does not increase because of the transfer.
The distinction is straightforward, but it can have significant implications for investors.
4. What Is the Difference Between an IPO and a Secondary Offering?
An initial public offering (IPO) is the first time a private company offers its shares to public investors and becomes publicly traded.
A secondary offering generally refers to a subsequent share offering by a company that is already public.
However, these terms should not be confused with the primary and secondary components of an IPO.
A traditional IPO may include:
- Newly issued shares sold by the company
- Existing shares sold by current shareholders
- A combination of both
Therefore, an IPO can contain both primary and secondary shares.
Example: A Company Goes Public
Imagine that a private company called GreenWave Energy decides to list its shares on Nasdaq.
The company issues 8 million new shares at $15 per share.
At the same time, one of its early investors sells 2 million existing shares at the same price.
The total offering is 10 million shares.
| Component | Shares Offered | Gross Proceeds | Recipient |
|---|---|---|---|
| Primary shares | 8 million | $120 million | GreenWave Energy |
| Secondary shares | 2 million | $30 million | Existing shareholder |
| Total | 10 million | $150 million | Both |
GreenWave Energy receives $120 million before offering expenses.
The existing investor receives $30 million before applicable expenses and taxes.
This is a combined IPO structure.
The company raises fresh capital, while the early investor gains partial liquidity.
Why Is This Distinction Important?
Investors sometimes assume that the entire amount announced in an IPO will be available to finance the company’s growth.
That is not necessarily true.
If an IPO includes a significant secondary component, part of the offering proceeds may go to existing shareholders.
This does not automatically make the offering unattractive. However, investors should understand the purpose and structure of the transaction before making an investment decision.
For a broader explanation of how IPO structures differ, see our guide to the different types of IPOs.
5. What Is a Follow-On Offering?
Another term investors should understand is follow-on offering.
A follow-on offering is a public share offering conducted by a company that is already publicly traded.
Unlike an IPO, it does not represent the company’s first entry into the public markets.
A follow-on offering may involve newly issued shares, existing shares sold by shareholders, or both.
This is where terminology can become confusing.
In U.S. market terminology, a follow-on offering may be:
A dilutive follow-on offering: The company issues new shares and receives the proceeds. The total share count increases.
A non-dilutive follow-on offering: Existing shareholders sell their shares. The company does not issue additional shares, and the proceeds go to the selling shareholders.
A combined follow-on offering: The transaction includes both newly issued shares and existing shareholder sales.
Example: A Public Company Raises Additional Capital
Suppose a publicly traded company has 50 million shares outstanding.
It wants to raise $120 million to finance a new manufacturing facility.
The company issues 4 million new shares at $30 each.
Gross proceeds:
4 million × $30 = $120 million
The total share count increases from 50 million to 54 million.
This is a dilutive follow-on offering.
Now imagine that an institutional shareholder sells 4 million existing shares at $30 each instead.
The transaction still has a gross value of $120 million, but the proceeds go to the shareholder.
The total share count remains 50 million.
This is a non-dilutive secondary sale.
The distinction is important because the same headline offering value can represent two very different transactions.
6. How Do Primary Offerings Affect Existing Shareholders?
One of the most important considerations in a primary offering is dilution.
When a company issues additional shares, existing shareholders own a smaller percentage of the business unless they also purchase enough new shares to maintain their ownership percentages.
However, dilution should not be evaluated in isolation.
Investors should consider whether the company can use the new capital to increase its future earnings and business value.
Example: Understanding Ownership Dilution
Consider a company with the following share structure:
- Existing shares outstanding: 40 million
- New shares issued: 10 million
- Total shares after the offering: 50 million
An investor owns 2 million shares.
Before the offering:
2 million ÷ 40 million = 5% ownership
After the offering:
2 million ÷ 50 million = 4% ownership
The investor’s ownership percentage falls from 5% to 4%.
However, suppose the company uses the capital to expand its business, increase revenue, and improve profitability.
If the resulting increase in business value is greater than the economic cost of issuing the new shares, existing shareholders may still benefit.
This is why investors should evaluate both dilution and the expected return on the capital raised.
Important Metrics to Monitor
Investors can examine several financial metrics when evaluating a primary offering:
- Shares outstanding before and after the transaction
- Earnings per share (EPS)
- Revenue growth
- Operating margins
- Return on invested capital (ROIC)
- Free cash flow
- Debt-to-equity ratio
- Expected capital expenditure
- Management’s stated use of proceeds
An increase in the share count is not automatically harmful. What matters is whether the additional capital contributes to sustainable value creation.
7. How Do Secondary Share Sales Affect Existing Shareholders?
A secondary sale of existing shares does not increase the total number of shares outstanding.
Instead, it changes who owns those shares.
Suppose a company has 100 million shares outstanding.
An institutional investor owns 10 million shares and decides to sell 3 million shares to other investors.
After the transaction:
- Total shares outstanding remain 100 million.
- The selling investor owns 7 million shares.
- New investors own the 3 million shares purchased.
- The company receives no proceeds from the sale.
Because no new shares are issued, there is no additional ownership dilution from the transaction itself.
However, secondary share sales can still influence the stock price.
Why Can a Secondary Sale Affect the Stock Price?
A large block of shares becoming available may increase the supply of stock in the market.
If demand is insufficient to absorb the additional shares, the stock price may come under pressure.
Investor sentiment can also influence the reaction.
For example, a large sale by a founder or senior executive may lead some investors to question the company’s prospects, even when the sale is motivated by personal financial planning.
On the other hand, a well-structured transaction that broadens the shareholder base may improve the distribution of ownership and trading liquidity.
The market reaction depends on the transaction size, pricing, shareholder identity, demand, and broader market conditions.
8. Why Do Companies Choose Primary Offerings Instead of Debt Financing?
A company that needs additional funding has several options.
It can borrow money, issue bonds, attract private investors, or issue new shares.
Primary equity offerings can be attractive because they provide capital without creating the same contractual repayment obligations as conventional borrowing.
Advantages of Equity Financing
No scheduled principal repayment: Unlike a traditional loan, newly issued equity does not require the company to repay the capital on a fixed maturity date.
Potentially lower financial leverage: Raising equity can improve the company’s debt-to-equity ratio.
Greater financial flexibility: The company may have more capacity to finance strategic investments without increasing debt obligations.
Support for long-term projects: Equity financing can be appropriate for projects that require substantial investment and may take years to generate cash flow.
Potential Disadvantages
Ownership dilution: Existing shareholders may own a smaller percentage of the company.
Shareholder expectations: Investors expect management to allocate capital efficiently and create value.
Offering expenses: Underwriting, legal, accounting, and advisory fees can be substantial.
Market dependence: The amount of capital a company can raise depends partly on investor demand and market conditions.
A company should therefore compare the cost of equity with the cost of debt and evaluate the impact on its long-term capital structure.
9. Why Do Existing Shareholders Sell Shares Through Secondary Offerings?
Secondary share sales can be important for the development of capital markets because they allow existing investors to realize the value of their holdings.
Private equity and venture capital investors, for example, often invest in businesses several years before they become publicly traded.
An IPO or subsequent secondary sale can create an opportunity to convert part of those investments into cash.
Liquidity for Early Investors
Early investors may have held shares for a long period without a readily available public market.
A secondary sale can allow them to realize part of their investment and distribute proceeds to their own investors.
Portfolio Diversification
Founders and early employees may have accumulated a substantial portion of their wealth through company shares.
Selling part of that position can reduce concentration risk.
Institutional Portfolio Management
Investment funds may sell shares to rebalance portfolios, manage risk, meet redemption requirements, or allocate capital to other opportunities.
Broader Share Ownership
A secondary offering can introduce additional investors to a company’s shareholder base.
However, investors should distinguish between increased trading activity and an actual improvement in business fundamentals.
10. What Should Investors Examine Before a Primary Offering?
A primary offering can create growth opportunities, but investors should evaluate how the company intends to use the money.
The following questions can help assess the transaction.
1. What Is the Purpose of the Capital Raise?
Look for specific explanations in the offering documents.
Does the company plan to expand production, develop new products, repay debt, or acquire another business?
A clearly defined use of proceeds is generally easier to evaluate than a vague statement about general corporate purposes.
2. Is the Company Financially Healthy?
Review revenue, profitability, cash flow, debt levels, and operating margins.
A company that raises capital to finance recurring operating losses may face a different risk profile from a profitable business raising funds for expansion.
3. How Much Dilution Will Occur?
Compare the number of shares outstanding before and after the offering.
Also consider options, warrants, convertible securities, and other instruments that could increase the share count in the future.
4. Can the Company Generate Attractive Returns on the New Capital?
Management should explain how the proposed investments support the company’s long-term strategy.
Investors should assess whether the expected returns justify the additional equity issued.
5. Is the Valuation Reasonable?
A company may have a strong growth strategy but still be offered at an unattractive valuation.
Compare its financial metrics with those of relevant competitors and consider the assumptions underlying its future growth.
For more guidance, read our article on how to use fundamental analysis to choose stocks.
11. What Should Investors Examine Before a Secondary Share Sale?
When existing shareholders sell shares, the company’s financing needs may not be the main reason for the transaction.
Investors should focus on the identity and intentions of the selling shareholders, as well as the market impact of the additional share supply.
1. Who Is Selling?
A sale by a venture capital fund may have a different context from a sale by a founder or senior executive.
Review the seller’s role, ownership history, and remaining stake.
2. How Large Is the Sale?
Compare the number of shares offered with:
- Total shares outstanding
- Public float
- Average daily trading volume
- The seller’s existing ownership
A sale representing a small percentage of the public float may have a different market impact from a transaction that introduces a large block of shares.
3. Is the Seller Retaining a Meaningful Stake?
If a major shareholder sells only part of its position and retains substantial ownership, its interests may remain aligned with the company’s long-term performance.
However, ownership percentage alone does not reveal the full picture. Voting rights and shareholder agreements may also matter.
4. Why Is the Transaction Taking Place?
Look for explanations in the company’s disclosures and offering documents.
The seller may be diversifying, distributing investment proceeds, or reducing an existing position.
5. Is the Offering Priced at a Significant Discount?
A secondary share sale may be priced at a discount to the prevailing market price to attract investors.
A discount can make the offering more attractive to buyers, but it may also place pressure on the stock price, particularly if the transaction is large.
12. Practical Example: Comparing a Primary and a Secondary Offering
Consider a fictional publicly traded company called Horizon Robotics.
The company currently has 60 million shares outstanding, trading at $25 each.
It needs additional funding for a new manufacturing facility and is considering a share offering.
Two possible structures are being evaluated.
Scenario A: Primary Offering
Horizon Robotics issues 4 million new shares at $25 each.
Gross proceeds:
4 million × $25 = $100 million
The company receives $100 million before offering expenses.
Its total shares outstanding increase from 60 million to 64 million.
The company plans to use the capital to build a new production facility.
Potential benefits:
- The company receives new financing.
- The funds can support future production capacity.
- The additional capital may strengthen its financial position.
Potential concerns:
- Existing shareholders experience ownership dilution.
- The company must generate sufficient returns on the new capital.
- The new facility may take time to become profitable.
Scenario B: Secondary Share Sale
An institutional shareholder sells 4 million existing shares at $25 each.
Gross proceeds:
4 million × $25 = $100 million
The institutional shareholder receives the proceeds.
The company receives no new capital.
The total share count remains 60 million.
Potential benefits:
- The selling shareholder gains liquidity.
- New investors may gain access to the stock.
- Ownership may become more widely distributed.
Potential concerns:
- The company does not receive financing for its new facility.
- The additional supply may affect the share price.
- Investors may question the reasons behind the shareholder’s decision to sell.
Scenario Comparison
| Metric | Primary Offering | Secondary Share Sale |
|---|---|---|
| Shares sold | 4 million | 4 million |
| Price per share | $25 | $25 |
| Gross transaction value | $100 million | $100 million |
| Proceeds received by company | $100 million | $0 |
| Proceeds received by seller | $0 | $100 million |
| Shares outstanding after transaction | 64 million | 60 million |
| Ownership dilution | Yes | No, from the sale itself |
The two transactions have the same gross value, but their effects on the company are completely different.
This is why investors should never rely only on the total amount of a share offering when evaluating a transaction.
13. Common Misconceptions About Primary and Secondary Offerings
Misconception 1: Every IPO Is Entirely a Primary Offering
Not necessarily.
An IPO can include newly issued shares, existing shares sold by shareholders, or both.
Investors should check the offering structure rather than assume that all proceeds go to the company.
Misconception 2: Secondary Share Sales Always Indicate a Lack of Confidence
Existing shareholders may sell for several reasons, including diversification and fund management.
A sale should be evaluated in context.
Misconception 3: Primary Offerings Are Always Better for Investors
A primary offering provides capital to the company, but the resulting dilution may not be justified if the funds are used inefficiently.
The quality of capital allocation matters.
Misconception 4: Secondary Offerings Always Reduce the Share Count
A secondary sale of existing shares does not reduce the total number of shares outstanding. It simply changes ownership.
Misconception 5: A Secondary Offering and Secondary Market Trading Are the Same Thing
They are not.
In the secondary market, investors buy and sell already-issued securities from one another through exchanges or other trading venues.
A secondary offering is a structured securities sale, often involving a company or existing shareholders distributing a block of shares to investors.
The terms are related, but they describe different activities.
Misconception 6: The Company Receives Money Whenever Its Shares Are Sold
The company receives proceeds when it issues and sells new shares.
When existing shareholders sell their shares, the proceeds generally go to those shareholders.
14. How to Identify Primary and Secondary Shares in an Offering Prospectus
The offering documents provide important information about the structure of a share sale.
In the United States, investors can review a company’s registration statement and prospectus through the SEC’s EDGAR database.
For an IPO, the registration statement is commonly filed on Form S-1.
For subsequent registered offerings, other forms may be used depending on the company’s reporting status and transaction structure.
The following sections are particularly useful.
The Offering Section
This section explains the number of shares being offered and identifies whether they are newly issued shares or existing shares held by selling shareholders.
Use of Proceeds
This section explains how the company intends to use the proceeds it receives.
If the offering includes shares sold by existing shareholders, the prospectus should distinguish those proceeds from the amounts received by the company.
Selling Shareholders
This section identifies shareholders who are offering their shares for sale.
Investors can examine their ownership positions before and after the transaction.
Capitalization
The capitalization section provides information about the company’s debt and equity structure.
It can help investors understand how a primary offering changes the company’s capital position.
Shares Eligible for Future Sale
Investors should also examine restrictions on existing shares, including lock-up arrangements and the conditions under which shares may become available for sale.
These disclosures can help investors assess potential changes in the supply of publicly tradable shares.
For additional information, consult the SEC’s guide to registered offerings.
15. Final Thoughts: Why the Difference Matters
Primary and secondary offerings may look similar because both involve the sale of shares to investors. However, their financial implications are fundamentally different.
A primary offering creates new shares and provides capital to the company. A secondary sale transfers existing shares from current shareholders to new investors, with the proceeds going to the sellers.
A combined offering can include both structures.
For investors, the most important questions are:
- Who is selling the shares?
- Is the company issuing new shares?
- Who receives the proceeds?
- How will the transaction affect ownership dilution?
- What is the purpose of the capital raise?
- Why are existing shareholders selling?
- Is the offering valuation reasonable?
Understanding these details helps investors move beyond the headline transaction value and evaluate what a share offering actually means for the company and its shareholders.
Ultimately, a primary offering can create opportunities for future growth, while a secondary sale can provide liquidity and change the ownership distribution. Neither structure guarantees a positive investment outcome. The company’s fundamentals, valuation, capital allocation, and market conditions remain essential.
Disclaimer: This article is for educational and informational purposes only. It does not constitute investment, legal, tax, or financial advice. Offering structures, disclosure requirements, and securities regulations vary by jurisdiction. Investors should review official offering documents and consider their individual circumstances before making investment decisions.