How to Protect Your Money From Inflation: A Guide to Preserving Wealth in High-Inflation Periods
Inflation does something surprisingly dangerous to your money.
It can make you feel financially secure while your purchasing power quietly declines.
You may have $100,000 in your bank account today.
Five years later, you may still have $100,000.
But if prices have risen significantly during that period, that $100,000 will buy considerably less.
This is the central problem with inflation.
Your account balance can remain stable while your wealth becomes weaker in real terms.
That is why the important question is not simply:
“How much money do I have?”
It is:
“How much purchasing power does my money still have?”
For long-term investors, this distinction is critical.
During periods of elevated inflation, holding excessive amounts of cash can become costly. At the same time, rushing into stocks, commodities, real estate, or other assets simply because inflation is high can create a different set of risks.
There is no single investment that automatically protects everyone from inflation.
The better approach is to understand how inflation affects different assets, evaluate your personal circumstances, and build a portfolio designed to preserve purchasing power over time.
30-Second Summary
- Inflation reduces the purchasing power of money over time.
- A stable bank balance does not necessarily mean stable wealth.
- The real return on an investment is its return after accounting for inflation.
- Cash is useful for liquidity but can lose purchasing power when inflation exceeds its yield.
- Stocks can provide long-term inflation protection because businesses can potentially raise prices and grow earnings.
- TIPS are specifically designed to adjust principal based on changes in the U.S. Consumer Price Index.
- Real estate and REITs can provide inflation-sensitive exposure, although they carry meaningful risks.
- Gold can diversify a portfolio but should not be treated as a guaranteed inflation hedge.
- Short-term Treasury securities and high-yield savings accounts can play an important role in liquidity management.
- Diversification is more important than trying to predict which asset will outperform during the next inflation spike.
- High inflation can also create behavioral risks, including FOMO, excessive trading, and speculative investing.
- The goal is not simply to earn a high nominal return. It is to preserve and grow purchasing power over the long term.
What Is Inflation and Why Is It Dangerous?
Inflation is the sustained increase in the prices of goods and services across an economy.
When inflation rises, the purchasing power of a dollar declines.
Suppose a basket of goods costs $1,000 today.
If prices rise by 5% over the next year, the same basket could cost approximately $1,050.
If your savings remain at $1,000 and generate no return, your money has lost purchasing power.
The dollar amount has not changed.
The economic value of that dollar has.
This is why inflation is sometimes described as a silent tax on cash.
It does not necessarily reduce the number shown in your bank account.
Instead, it reduces what that balance can buy.
Nominal Return vs. Real Return
One of the most important concepts for inflation-conscious investors is the difference between nominal and real returns.
Nominal return is the percentage increase in the dollar value of an investment.
Real return is the return after accounting for inflation.
For example, imagine your investment earns 7% in one year.
If inflation is 3%, your approximate real return is around 4%.
Now imagine the investment earns 7% while inflation is 8%.
Your nominal balance increased.
But your purchasing power declined.
The exact real return can be calculated using:
Real Return = (1 + Nominal Return) / (1 + Inflation Rate) – 1
This formula is more precise than simply subtracting inflation from the nominal return.
The broader lesson is simple:
Always evaluate investment returns in real terms.
The Hidden Cost of Keeping Too Much Cash
Cash is not inherently bad.
In fact, cash is essential for financial stability.
You need money for:
- Emergency expenses
- Rent or mortgage payments
- Insurance deductibles
- Near-term purchases
- Unexpected financial emergencies
- Short-term investment opportunities
The problem arises when long-term wealth is kept entirely in cash.
Imagine you have $100,000 sitting in a checking account that earns almost no interest.
If inflation averages 5% for several years, your nominal balance may remain approximately $100,000.
But the purchasing power of that balance can decline significantly.
This is why investors need to distinguish between:
Cash for financial security
and
Cash being used as a long-term investment strategy.
Those are two very different things.
How Much Cash Should You Keep?
There is no universal number.
Your appropriate cash reserve depends on your income stability, household expenses, debt, employment situation, and financial goals.
Many households choose to maintain several months of essential expenses in an emergency fund.
That money should prioritize liquidity and safety rather than maximum returns.
For money you may need soon, protecting principal can be more important than maximizing growth.
For money you will not need for decades, however, the situation is different.
Long-term capital may need exposure to assets with greater potential to outpace inflation.
1. Stocks: Can Equities Protect Against Inflation?
Stocks are among the most important long-term tools for protecting purchasing power.
Why?
Because when you own shares of a company, you own a claim on a productive business.
A strong business may be able to:
- Raise prices
- Increase revenue
- Expand its customer base
- Improve productivity
- Grow earnings
- Increase dividends
- Generate more free cash flow
Companies with strong pricing power can sometimes pass higher input costs on to customers.
That can help protect margins during inflationary periods.
However, not every stock is an inflation hedge.
Some businesses are extremely sensitive to higher interest rates, rising labor costs, commodity prices, or weaker consumer demand.
This is why simply buying stocks because inflation is high is not a complete strategy.
The quality of the underlying businesses matters.
What Types of Companies May Be More Resilient During Inflation?
Investors may pay particular attention to companies with characteristics such as:
- Strong pricing power
- Recurring revenue
- Healthy free cash flow
- Low or manageable debt
- Strong brands
- Essential products or services
- International revenue
- High returns on invested capital
- Flexible cost structures
Examples can include businesses in areas such as consumer staples, healthcare, infrastructure, energy, and certain technology or software companies.
But sector labels alone are not enough.
A poorly managed company in a supposedly defensive industry can still produce disappointing returns.
Investors should focus on the economics of the individual business.
2. Treasury Inflation-Protected Securities (TIPS)
For U.S. investors, one of the most direct tools for inflation protection is Treasury Inflation-Protected Securities, commonly known as TIPS.
TIPS are U.S. government securities whose principal value adjusts with changes in the Consumer Price Index.
When inflation rises, the principal can increase.
Interest payments are then calculated based on the adjusted principal.
This makes TIPS fundamentally different from ordinary fixed-rate bonds.
Traditional bonds can lose purchasing power when inflation rises unexpectedly because their fixed payments become less valuable in real terms.
TIPS are specifically structured to provide protection against inflation-related changes in purchasing power.
However, TIPS are not risk-free investments in every sense.
Their market prices can fluctuate as interest rates change, especially when you sell before maturity.
They should therefore be viewed as one component of a broader portfolio rather than a universal solution.
3. Treasury Bills and Short-Term Government Securities
Short-term U.S. Treasury securities can also play an important role during periods of elevated inflation and interest rates.
Treasury bills, for example, mature in one year or less.
They generally provide much more liquidity and lower price sensitivity than long-duration bonds.
When short-term interest rates rise, newly issued Treasury securities can offer higher yields.
This can make short-duration fixed income more attractive than leaving large balances in a low-yield checking account.
But investors should remember an important distinction:
A positive nominal yield does not automatically mean a positive real return.
If inflation is higher than your after-tax investment return, purchasing power can still decline.
4. High-Yield Savings Accounts
A high-yield savings account can be useful for money that needs to remain liquid.
It may provide a significantly better interest rate than a traditional checking account.
This makes it particularly useful for emergency funds and short-term goals.
However, savings accounts should not automatically be considered long-term inflation hedges.
Their rates can change as monetary policy changes.
If inflation remains elevated for a long period, your purchasing power may still decline even while the account earns interest.
The appropriate question is therefore:
“What is my after-tax real return?”
5. Gold as an Inflation and Crisis Hedge
Gold has been used as a store of value for centuries.
During periods of:
- Economic uncertainty
- Currency instability
- Geopolitical stress
- Financial-market turmoil
- Concerns about inflation
investors may increase their exposure to gold.
Gold can provide diversification because its performance drivers are different from those of many financial assets.
But there is an important caveat.
Gold is not a guaranteed short-term inflation hedge.
Gold prices can be volatile.
They can also respond to interest rates, real yields, currency movements, central-bank demand, and investor sentiment.
Gold therefore may have a role in a diversified portfolio, but relying entirely on gold to protect wealth can create concentration risk.
6. Real Estate and REITs
Real estate is another asset class frequently associated with inflation protection.
Property owners may benefit from:
- Higher rents over time
- Potential property appreciation
- Replacement-cost increases
- Long-term demand for real assets
However, real estate is not automatically an inflation-proof investment.
Higher inflation often comes with higher interest rates.
Higher borrowing costs can pressure property valuations and increase financing expenses.
Real estate is also relatively illiquid compared with publicly traded securities.
For investors who want real-estate exposure without directly purchasing a property, REITs can provide another option.
Publicly traded REITs are more liquid, but their market prices can be volatile and sensitive to interest rates.
7. Commodities and Natural Resources
Commodities can sometimes perform strongly during inflationary periods.
Energy, metals, agricultural products, and other raw materials can experience price increases when supply is constrained or demand is strong.
However, commodities are highly cyclical.
Prices can rise sharply and then fall sharply.
They generally do not produce cash flow in the same way that stocks, bonds, or rental properties can.
For that reason, commodities are usually better viewed as a potential diversification tool than as the foundation of a long-term portfolio.
8. International Investments and Currency Diversification
Inflation is not always equally severe across countries.
Investors whose wealth is concentrated entirely in one currency may face additional purchasing-power risk if that currency weakens.
International stocks and other global investments can provide exposure to different economies and currencies.
However, currency diversification introduces its own risks.
Exchange rates can move sharply.
A foreign investment can perform well in its local currency but produce a different result after converting the return into U.S. dollars.
International diversification should therefore be considered as part of overall portfolio construction rather than as a simple currency hedge.
A Realistic Example: Two Investors During High Inflation
Consider two American investors, Michael and Sarah.
Both have $200,000.
Michael keeps nearly all of his money in cash because he wants to avoid market volatility.
Sarah maintains an emergency fund but invests her long-term capital across a diversified mix of equities, inflation-sensitive assets, and fixed income.
Inflation remains elevated for several years.
Michael’s account balance may look reassuring.
But if his cash yield consistently falls below inflation, his purchasing power declines.
Sarah’s portfolio experiences volatility.
Some investments perform poorly during certain periods.
Others perform better.
Her portfolio is not guaranteed to beat inflation every year.
But the structure gives her exposure to productive assets and inflation-sensitive investments that may have a better chance of preserving long-term purchasing power.
The important difference is not that Sarah eliminated risk.
She diversified the sources of risk.
The Real Goal Is Not to Beat Inflation Every Year
This is an important point.
Some investors become obsessed with finding an asset that beats inflation every single year.
That is unrealistic.
Even excellent investments can experience temporary periods of negative real returns.
The better objective is to construct a portfolio that has a reasonable probability of preserving and growing purchasing power over your investment horizon.
For a 20- or 30-year investor, one bad year does not define financial success.
The long-term compounding process matters far more.
Why Diversification Matters During Inflation
One of the biggest mistakes investors make during inflation is searching for a single perfect asset.
They may decide:
“Gold is the answer.”
Or:
“Stocks are the answer.”
Or:
“Real estate always beats inflation.”
These statements are too simplistic.
Different assets respond differently to:
- Interest rates
- Economic growth
- Inflation expectations
- Currency movements
- Government policy
- Investor sentiment
- Corporate earnings
Diversification allows investors to avoid making one giant bet on one economic outcome.
Inflation Can Change Your Investment Strategy
Inflation can influence more than asset selection.
It can also affect how you evaluate companies.
For example, consider a company with $1 billion in debt.
If its borrowing costs rise significantly, interest expenses may increase.
That can reduce earnings and free cash flow.
Companies with excessive debt can therefore become more vulnerable in a high-rate environment.
By contrast, businesses with strong balance sheets may have more flexibility.
This is why investors should look beyond revenue growth.
During inflationary periods, examine:
- Debt levels
- Interest coverage
- Free cash flow
- Operating margins
- Pricing power
- Return on invested capital
Pricing Power Is Especially Important
Imagine two companies.
Company A sells a product for $10.
Its costs rise from $7 to $8.50 because of inflation.
If it cannot raise prices, its margin falls sharply.
Company B has a strong brand and loyal customers.
Its price rises from $10 to $11.50.
If demand remains relatively stable, the company may preserve more of its profitability.
This is why pricing power is an important qualitative factor for inflation-sensitive investors.
Businesses selling essential or differentiated products may have greater ability to pass some cost increases to customers.
Inflation and Dividend Stocks
Dividend-paying stocks can also play a role in a long-term inflation-conscious portfolio.
But investors should avoid focusing solely on dividend yield.
A very high yield can sometimes signal that the market expects a dividend cut or that the underlying business is struggling.
What matters is the sustainability and growth of the dividend.
Investors can examine:
- Free cash flow
- Payout ratio
- Dividend growth history
- Debt levels
- Earnings stability
A growing dividend can potentially help investors maintain purchasing power over long periods, especially when supported by growing earnings and cash flow.
Inflation and Your Salary
Protecting wealth is not only about investments.
Your income is also an economic asset.
Imagine your salary rises 4% while inflation is 7%.
Your nominal income increased.
Your real purchasing power declined.
This is why improving your earning power can be an important part of inflation protection.
Skills, professional certifications, career development, and negotiating compensation can all contribute to long-term financial resilience.
The strongest inflation strategy therefore combines:
- Income growth
- Expense control
- Emergency savings
- Debt management
- Investing
Inflation Can Also Change Your Spending Behavior
High inflation can create unusual psychological pressure.
People may start thinking:
“If prices are going to keep rising, I should buy it now.”
Sometimes that makes sense.
But it can also encourage unnecessary consumption.
For example, someone may buy a more expensive car, electronics, or luxury goods simply because they fear prices will rise further.
This can create a dangerous cycle:
Inflation fear → accelerated consumption → lower savings → weaker investment capacity.
A disciplined financial plan can help prevent this.
Our guide to financial minimalism explores how intentional spending can create more capital for long-term wealth building.
Inflation and FOMO
Inflation can also trigger investment FOMO.
You may hear that:
- Gold is exploding
- Real estate is going up
- Commodities are soaring
- A particular stock is “inflation-proof”
- A new investment trend is generating huge returns
Suddenly, investors feel that they are falling behind.
That feeling can lead to impulsive decisions.
The problem is that by the time a trend becomes obvious, its valuation may already reflect much of the optimism.
Inflation protection should therefore be based on portfolio design, not social-media excitement.
The Most Dangerous Inflation Mistake: Concentration
When people become afraid of losing purchasing power, they sometimes put everything into one asset.
That can be extremely dangerous.
Imagine putting your entire savings into:
- Gold
- One stock
- One property
- A single currency
- One commodity
If the asset underperforms, your entire financial position suffers.
Diversification does not guarantee profits.
But it can prevent one incorrect economic forecast from destroying your portfolio.
Should You Move Everything Into Inflation-Protected Assets?
Usually, no.
The term “inflation-protected asset” can be misleading.
No asset is perfectly protected against every form of inflation and every market environment.
Even TIPS can fluctuate in market value.
Real estate can decline.
Stocks can fall sharply.
Gold can experience long periods of weak performance.
Commodities can collapse after supply conditions change.
The goal is not to eliminate every risk.
The goal is to build a portfolio where different assets can respond differently to changing economic conditions.
A Practical Inflation-Protection Framework
Instead of searching for one perfect investment, consider a five-step framework.
Step 1: Protect Your Short-Term Liquidity
Maintain an emergency fund appropriate for your circumstances.
Do not invest money that you may need for essential expenses in the near future.
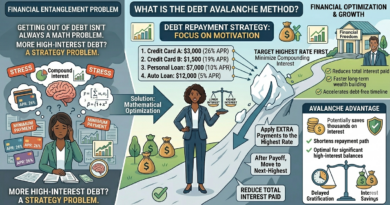
Step 2: Reduce Expensive Debt
High-interest consumer debt can overwhelm investment returns.
Reducing expensive debt can provide a relatively predictable financial benefit.
Step 3: Invest Long-Term Capital
Capital that you will not need for many years can potentially be allocated to productive assets such as diversified equities and other investments appropriate to your risk profile.
Step 4: Add Inflation-Sensitive Exposure Where Appropriate
Depending on your circumstances, this could include TIPS, real estate, REITs, commodities, gold, or other assets.
Step 5: Review the Portfolio Periodically
Inflation changes.
Interest rates change.
Your financial situation changes.
Your portfolio should therefore be reviewed periodically rather than treated as a permanent set of positions.
A Sample Conceptual Portfolio
There is no universally correct inflation-proof portfolio.
However, a conceptual diversified structure might include several different categories:
- Liquidity: Emergency savings and short-term cash reserves
- Inflation-linked fixed income: TIPS
- Growth assets: Diversified U.S. and international equities
- Real assets: Real estate or REIT exposure
- Diversifiers: Potentially gold or other appropriate assets
The actual allocation should depend on age, goals, income, risk tolerance, tax situation, and investment horizon.
This is a framework for thinking, not a one-size-fits-all investment recommendation.
What About 401(k)s and IRAs?
Inflation protection should also be considered within retirement planning.
For U.S. investors, tax-advantaged accounts such as:
- 401(k)s
- Traditional IRAs
- Roth IRAs
- Health Savings Accounts, when eligible
can be important components of long-term wealth building.
The account type itself does not protect you from inflation.
The investments held inside the account matter.
A retirement account invested entirely in cash may have limited long-term growth potential.
A diversified portfolio of productive assets may have greater potential to outpace inflation over a long horizon, although with higher short-term volatility.
Why Long-Term Thinking Matters
Inflation can make investors extremely short-term oriented.
People start focusing on:
- Next month’s inflation report
- The next Federal Reserve meeting
- Tomorrow’s gold price
- This week’s stock-market movement
These factors can matter.
But long-term wealth is generally built over years and decades.
If you are investing for retirement 25 years from now, reacting to every monthly inflation number can become counterproductive.
A better question is:
“Is my portfolio structurally capable of growing purchasing power over my investment horizon?”
Common Mistakes Investors Make During High Inflation
1. Keeping Everything in Cash
Cash provides security and liquidity, but excessive cash can lose purchasing power.
2. Buying Whatever Has Recently Risen
Past performance does not guarantee future inflation protection.
3. Putting Everything Into Gold
Gold can diversify a portfolio but can also experience substantial volatility.
4. Ignoring Interest-Rate Risk
Higher inflation can lead to higher interest rates, which can pressure bonds, real estate, and highly leveraged companies.
5. Ignoring Taxes
Investment returns should be evaluated after taxes and inflation, not simply by looking at the headline return.
6. Using Too Much Leverage
Debt can amplify both gains and losses.
7. Chasing Inflation-Proof Investments
No investment is perfectly protected in every economic environment.
8. Abandoning Long-Term Investing
Constantly changing strategies can make it harder to benefit from compounding.
How to Protect Wealth Without Trying to Predict the Future
One of the biggest misconceptions about inflation investing is that you need to correctly predict the next economic environment.
You do not.
You can build a portfolio designed to function across multiple environments.
For example:
- Stocks can provide long-term growth.
- Bonds can provide income and diversification.
- TIPS can provide inflation-linked exposure.
- Cash provides liquidity.
- Real estate can provide exposure to physical assets and rental income.
- Gold can provide diversification.
The objective is not to know which asset will win.
The objective is to avoid needing one asset to win.
Frequently Asked Questions About Protecting Money From Inflation
How can I protect my money from inflation?
There is no single solution. A combination of appropriate cash reserves, diversified equities, inflation-linked bonds such as TIPS, real assets, and disciplined long-term investing can help protect purchasing power.
Is cash a good investment during inflation?
Cash is valuable for liquidity and emergencies, but it can lose purchasing power if its yield remains below inflation for an extended period.
What is the best investment during high inflation?
There is no universally best investment. The appropriate strategy depends on your time horizon, risk tolerance, financial goals, and the type of inflation affecting the economy.
Do stocks protect against inflation?
Over long periods, stocks can potentially outpace inflation because companies can increase prices, revenue, earnings, and cash flow. However, stocks can perform poorly during individual inflationary periods.
What are TIPS?
TIPS are Treasury Inflation-Protected Securities issued by the U.S. government. Their principal adjusts with changes in the Consumer Price Index, providing direct inflation-linked exposure.
Are TIPS completely risk-free?
TIPS have very low credit risk because they are backed by the U.S. government, but their market value can fluctuate before maturity due to changes in interest rates and market conditions.
Does gold protect against inflation?
Gold can provide diversification and may perform well during certain inflationary or uncertain environments. However, it is not guaranteed to outperform inflation over every period.
Is real estate a good inflation hedge?
Real estate can benefit from rising rents and property values in some inflationary environments, but higher interest rates, financing costs, vacancies, and property-specific risks can negatively affect returns.
Can REITs protect against inflation?
REITs provide exposure to income-producing real estate and may benefit from rising rents in certain environments. However, publicly traded REITs can be sensitive to interest rates and stock-market volatility.
Should I buy Treasury bonds when inflation is high?
It depends on the type and maturity of the bond. Short-term Treasuries can provide attractive yields when rates are high, while TIPS provide explicit inflation-linked protection. Traditional long-duration bonds can be more sensitive to rising interest rates.
Should I invest all my money in inflation-protected assets?
Generally, concentrating your entire portfolio in one category creates unnecessary risk. Diversification is usually more robust than trying to predict which single asset will outperform.
How does inflation affect retirement savings?
Inflation can reduce the future purchasing power of retirement savings. This makes long-term growth and appropriate asset allocation particularly important for investors with long retirement horizons.
Should I change my 401(k) because of inflation?
Not necessarily. Your 401(k) is an account, not an investment itself. Review the investments inside the account and make sure your overall allocation remains appropriate for your goals and risk tolerance.
Can international investments help protect against inflation?
International investments can provide exposure to different economies, companies, and currencies. They can improve diversification, although currency and foreign-market risks remain.
Why is diversification important during inflation?
Different assets respond differently to inflation, interest rates, economic growth, and market sentiment. Diversification reduces dependence on any single economic outcome.
Should I buy stocks because inflation is high?
Not simply because inflation is high. Evaluate the company’s pricing power, debt, cash flow, valuation, competitive position, and long-term growth prospects.
How does inflation affect dividend stocks?
Companies with sustainable and growing dividends may help provide income that can increase over time. However, investors should examine the sustainability of dividends rather than focusing only on dividend yield.
Can inflation make me poorer even if my salary increases?
Yes. If your salary increases more slowly than the cost of living, your real purchasing power can decline despite a higher nominal income.
Final Thoughts: Protect Purchasing Power, Not Just Your Account Balance
Inflation changes the meaning of money.
A dollar today is not necessarily equivalent to a dollar ten years from now.
That is why successful long-term investing requires looking beyond nominal account balances.
The real objective is purchasing power.
Protecting wealth during inflation does not mean finding one magical investment.
It means building a financial system that can adapt to changing economic conditions.
Keep enough cash for emergencies.
Reduce expensive debt.
Invest long-term capital in productive assets.
Consider inflation-linked securities such as TIPS when appropriate.
Use diversification rather than making a single massive bet.
Understand the businesses you own.
Pay attention to pricing power, debt, cash flow, and valuation.
And most importantly, avoid making emotional decisions simply because inflation headlines become frightening.
High inflation can create uncertainty.
But uncertainty does not mean you need to abandon a disciplined financial plan.
The most resilient investors understand that the goal is not to predict exactly what inflation, interest rates, stocks, gold, or real estate will do next.
The goal is to build a portfolio capable of surviving different economic environments.
Because protecting wealth is not about finding the perfect asset. It is about creating a system that protects your purchasing power over time.
That system may look different for every investor.
But the principle remains the same:
Earn. Save. Invest. Diversify. Think in real returns. And let time work in your favor.