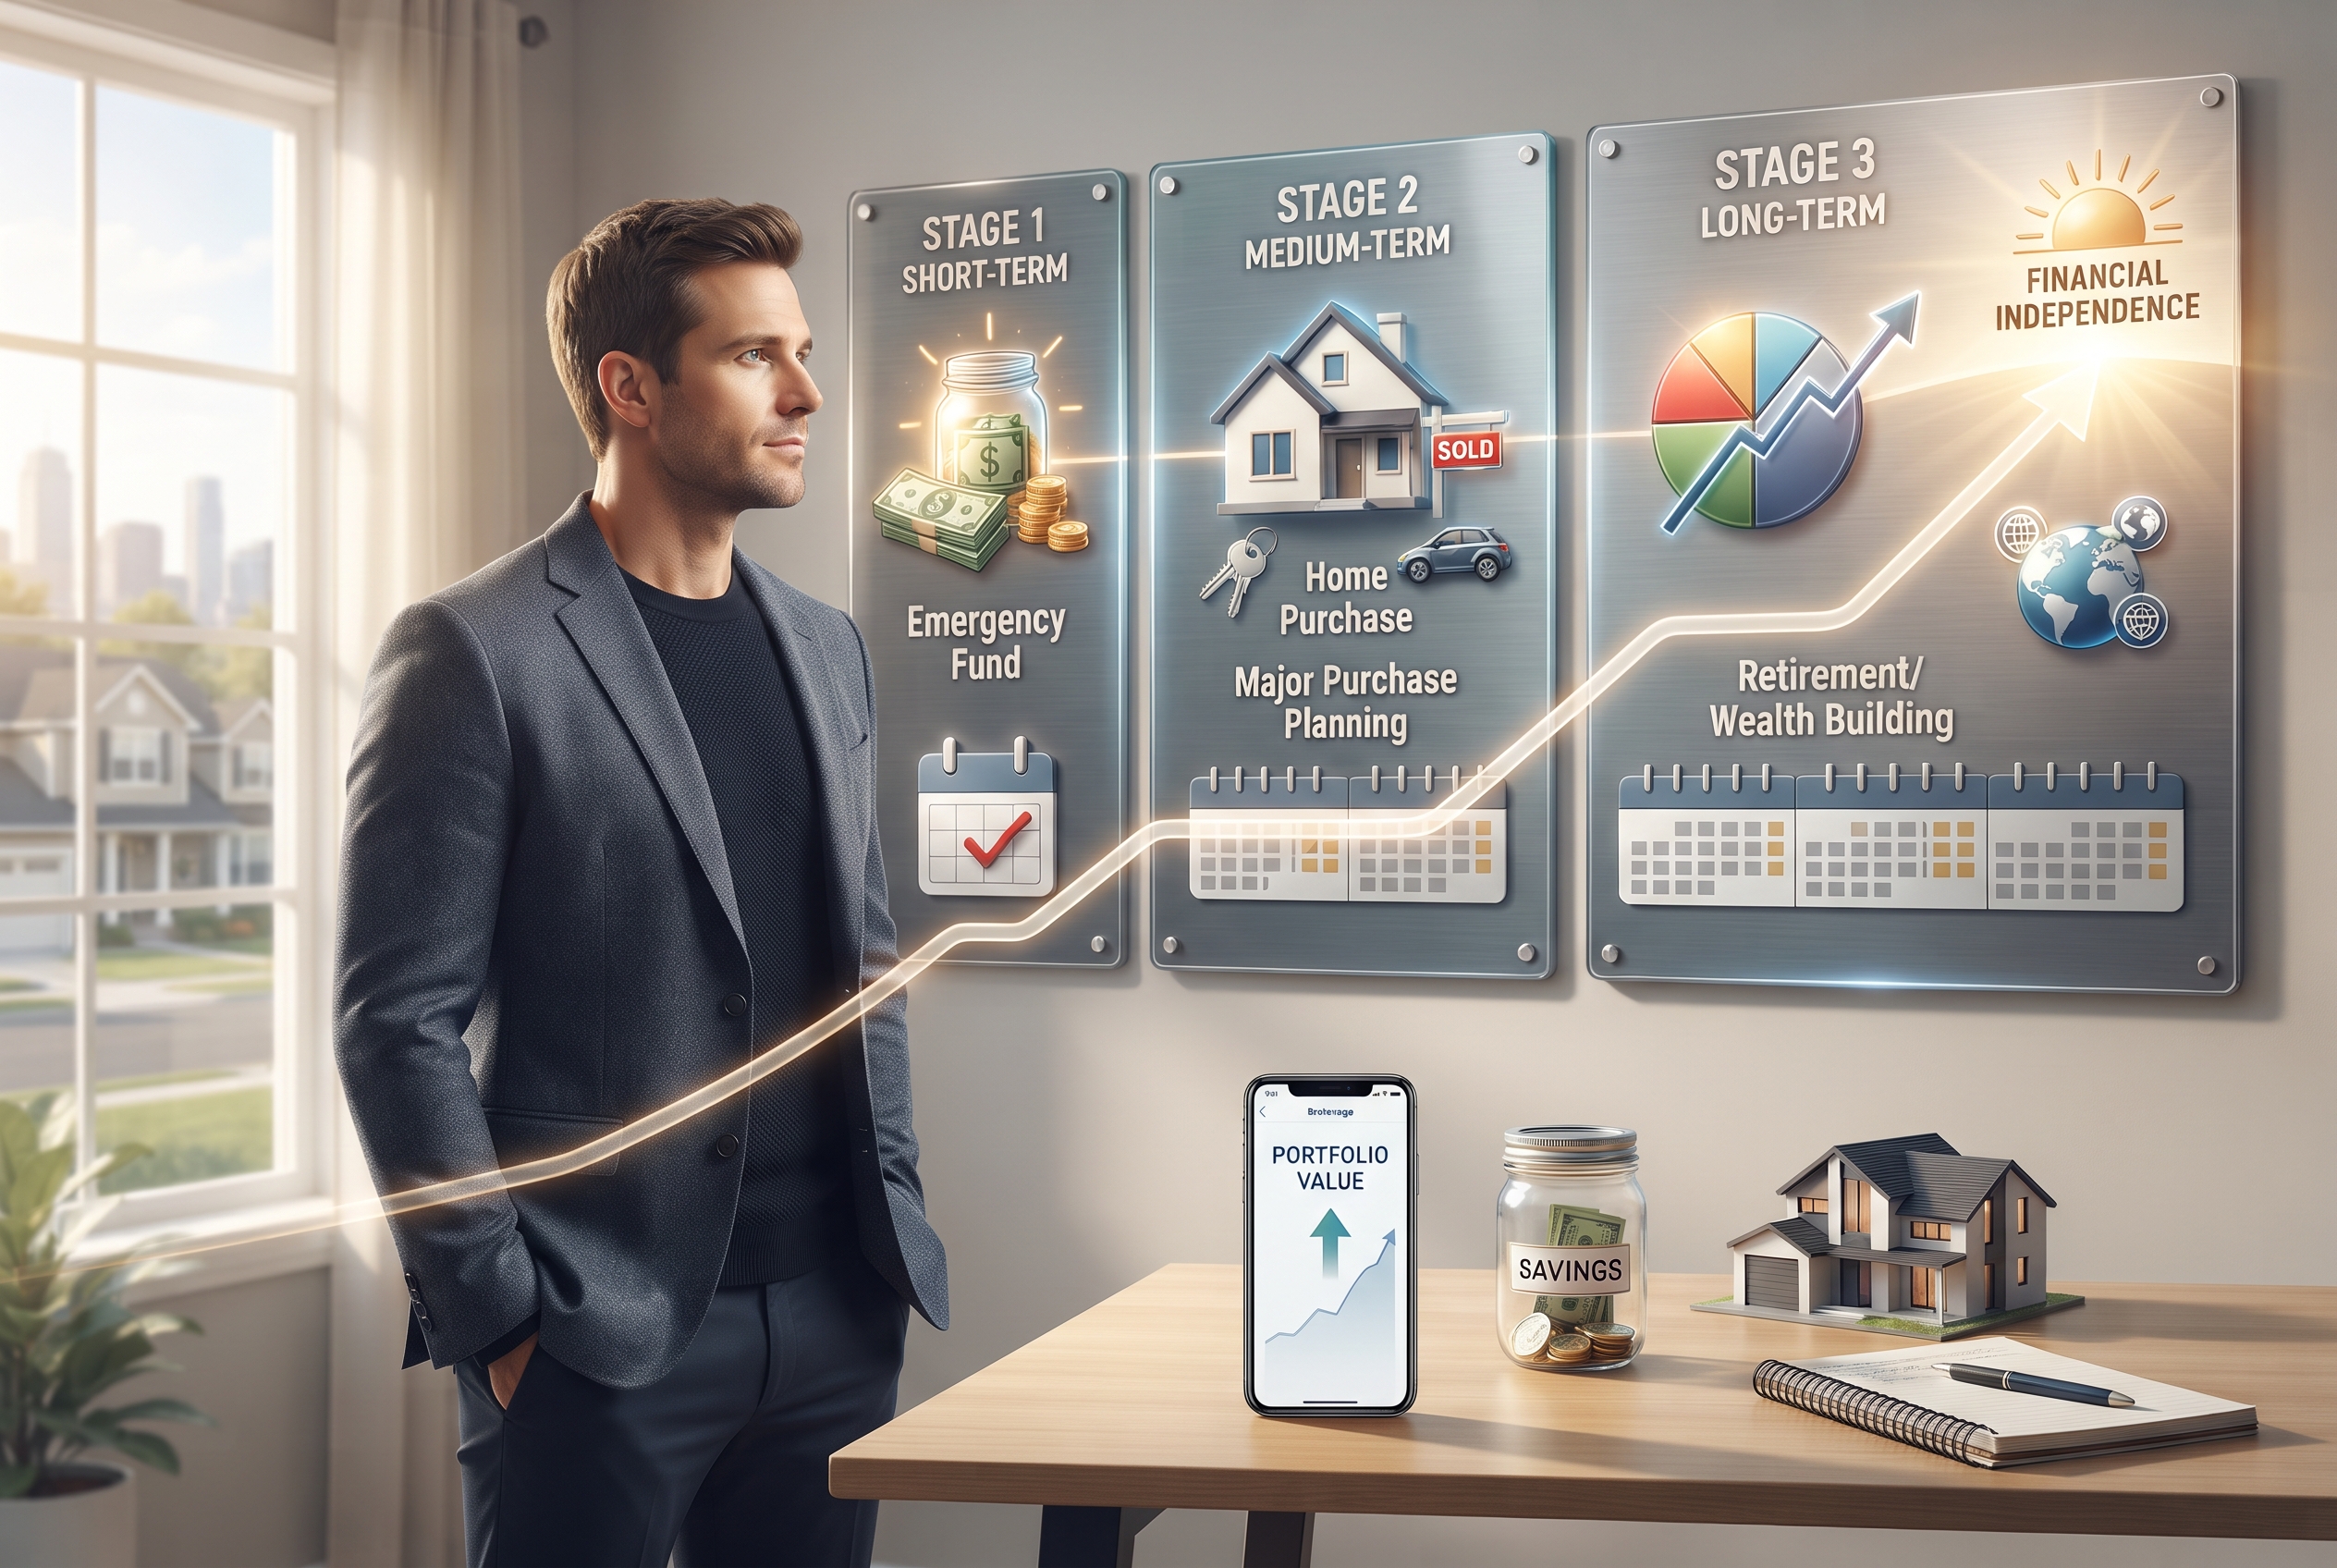
How to Set Financial Goals: A Short-, Medium-, and Long-Term Goal System
“I want to save more money.”
“I want to start investing.”
“I want to buy a house.”
“I want to retire comfortably.”
These are all reasonable financial ambitions.
But they are not yet financial goals.
A real financial goal tells you what you want to achieve, how much money you need, when you need it, and what you need to do between today and that future date.
That distinction matters because money without a destination is easy to spend, while money connected to a clearly defined goal can become part of a financial system.
For an investor, financial goals are also the starting point for deciding how much to save, how much risk to take, what type of account to use, and what investment horizon makes sense.
- A financial goal should include a purpose, a dollar amount, and a target date.
- Financial goals can be organized into short-, medium-, and long-term categories.
- Your investment time horizon should influence how much market risk you can reasonably take.
- Short-term goals generally require greater emphasis on liquidity and capital preservation.
- Long-term goals such as retirement may allow more exposure to growth-oriented investments, depending on your risk tolerance and circumstances.
- SMART goals—Specific, Measurable, Achievable, Relevant, and Time-bound—can turn vague financial intentions into actionable plans.
- Prioritizing goals is essential because income and savings capacity are limited.
- Emergency savings and high-interest debt may need attention before aggressive long-term investing.
- Your financial goals should be reviewed periodically because income, expenses, family circumstances, and market conditions can change.
- The right investment is not determined by the investment alone; it depends partly on the goal the money is intended to fund.
What Is a Financial Goal?
A financial goal is a measurable economic objective that you want to achieve within a defined period.
For example:
| Vague Intention | Specific Financial Goal |
|---|---|
| I want to save more. | Save $12,000 for an emergency fund within 12 months. |
| I want to buy a house. | Build a $100,000 down payment within five years. |
| I want to invest. | Invest $750 per month toward long-term retirement savings. |
| I want to retire comfortably. | Build a retirement portfolio capable of supporting my planned retirement spending. |
| I want to pay off debt. | Eliminate $15,000 of high-interest credit-card debt within 24 months. |
The difference is simple:
A financial wish describes what you would like to happen. A financial goal gives you a measurable destination.
Why Financial Goals Matter
Your income alone does not determine your financial progress.
Two people can earn the same salary and end up in completely different financial positions because they have different spending patterns, debt levels, savings rates, investment habits, and goals.
Financial goals create a connection between today’s decisions and tomorrow’s priorities.
For example, consider someone earning $100,000 per year.
If that person simply says, “I want to become wealthier,” there is no clear action plan.
But if the goal is:
“I want to build a $30,000 emergency fund, eliminate my high-interest debt, and invest $1,000 per month toward retirement,”
the financial priorities become much clearer.
This is also why financial goals are closely connected to money management and budgeting.
Your budget determines what you can allocate today. Your financial goals determine where that money should ultimately go.
Financial Goals vs. Financial Dreams
Dreams are important because they provide motivation.
But dreams usually need to be translated into numbers and dates before they can become actionable.
| Financial Dream | Financial Goal |
|---|---|
| Become wealthy | Build a diversified investment portfolio worth a defined amount over a specific time period. |
| Buy a house | Save a specific down payment within five years. |
| Become debt-free | Pay off $20,000 of high-interest debt within 18 months. |
| Help my children with college | Contribute a specific monthly amount to a college savings account until enrollment. |
| Retire comfortably | Accumulate enough retirement assets to support a defined spending target. |
There is nothing wrong with having ambitious financial dreams.
The problem begins when the dream never becomes a plan.
The Four Questions Every Financial Goal Should Answer
A useful financial goal should answer four basic questions:
- What? What exactly do I want to accomplish?
- How much? What financial amount is involved?
- When? When do I need to achieve it?
- Why? Why does this goal matter to me?
The fourth question is often overlooked.
But motivation matters.
Saving $20,000 simply because you think you “should” may not be enough to sustain the behavior.
Saving $20,000 because it represents the first step toward buying your first home can create a much stronger connection between today’s sacrifice and tomorrow’s benefit.
How to Set Financial Goals Step by Step
A practical financial goal system can be built through the following process:
- Understand your current financial position.
- Identify what matters most in your life.
- Translate those priorities into financial goals.
- Assign a dollar amount to each goal.
- Set a target date.
- Classify the goal by time horizon.
- Prioritize your goals.
- Calculate the required savings or investment contribution.
- Choose financial products appropriate for the goal and time horizon.
- Track progress and revise the plan when circumstances change.
Step 1: Understand Your Current Financial Position
Before deciding where you want to go, determine where you are.
At minimum, calculate:
| Financial Metric | Question |
|---|---|
| Net income | How much money actually reaches my bank account each month? |
| Essential expenses | How much do I need to cover basic living costs? |
| Discretionary spending | Which expenses could be reduced if necessary? |
| Debt | How much do I owe and at what interest rates? |
| Emergency savings | How much liquid cash do I have available? |
| Investments | What stocks, bonds, ETFs, retirement accounts, or other assets do I own? |
| Net worth | What do I own minus what I owe? |
This exercise can reveal whether a goal is realistic.
For example, deciding to invest $2,000 every month sounds straightforward until you discover that your current monthly surplus is only $800.
The problem is not necessarily the goal.
The problem is the gap between the goal and the current financial system.
Step 2: Connect Financial Goals to Your Life Goals
Money is a tool.
Therefore, financial planning should begin with the life you want to build rather than simply the size of the investment account you want to see.
Ask yourself:
- Do I want to buy a home?
- Do I want to retire early?
- Do I want to reduce financial stress?
- Do I want to help fund my children’s education?
- Do I want more flexibility in my career?
- Do I want to travel more?
- Do I want to become financially independent?
- Do I want to build a business?
Each of these ambitions has a financial dimension.
For example, “I want more career flexibility” might eventually become:
“I want enough invested assets and cash reserves to cover my living expenses for 12 months if I leave my current job.”
That is now a financial goal.
Step 3: Turn the Goal Into a Dollar Amount
This is where a vague ambition becomes measurable.
Suppose you want to buy a home in five years.
Your target is a $500,000 home and you want a $100,000 down payment.
If you already have $25,000 saved specifically for the down payment, the remaining gap is:
$100,000 − $25,000 = $75,000
Ignoring investment returns for a moment, the basic monthly savings requirement would be:
$75,000 ÷ 60 months = $1,250 per month
This is only a simple planning calculation.
Real-world planning may also need to consider:
- Home-price changes
- Inflation
- Investment returns
- Taxes
- Fees
- Changes in income
- Changes in the desired purchase date
The purpose of the basic calculation is not to predict the future perfectly. It is to establish a starting point.
Step 4: Use the SMART Framework
One of the most widely used frameworks for turning vague financial intentions into actionable goals is the SMART framework.
| SMART Element | Meaning | Financial Example |
|---|---|---|
| Specific | Clearly defined | Build an emergency fund |
| Measurable | Can be quantified | Save $15,000 |
| Achievable | Realistic within your circumstances | Fits your income and expenses |
| Relevant | Connected to an important priority | Protect against unexpected expenses |
| Time-bound | Has a deadline | Complete within 12 months |
The Consumer Financial Protection Bureau uses this framework in its financial education resources, emphasizing that specific, measurable, attainable, relevant, and time-bound goals can make financial intentions more actionable.
Step 5: Divide Goals Into Short-, Medium-, and Long-Term
Not every dollar has the same time horizon.
This is one of the most important ideas in financial planning.
Money you need next year should generally be managed differently from money you expect to use 25 years from now.
Investor.gov defines time horizon as the number of months, years, or decades you need to invest to achieve a financial goal. It also notes that time horizon and risk tolerance are important factors in determining an appropriate asset allocation.
Short-Term Financial Goals
Short-term goals are generally goals that need to be funded within the next few months or several years.
Examples include:
- Building an emergency fund
- Paying off high-interest credit-card debt
- Saving for a vacation
- Replacing a vehicle
- Preparing for a major upcoming expense
- Building a cash reserve
For these goals, liquidity and capital preservation can be more important than maximizing investment returns.
If you know you need $20,000 for a home renovation next year, a highly volatile stock portfolio may create a mismatch between your investment strategy and your financial goal.
Medium-Term Financial Goals
Medium-term goals often fall somewhere around the two-to-five-year range, although the exact definition can vary.
Examples include:
- Building a home down payment
- Starting a business
- Funding graduate school
- Replacing a vehicle
- Preparing for a major family expense
- Paying down a substantial debt balance
These goals require a careful balance between growth, risk, and liquidity.
The closer the deadline becomes, the less time you have to recover from a significant market decline.
Long-Term Financial Goals
Long-term goals typically extend beyond five years and may last for decades.
Examples include:
- Retirement
- Financial independence
- Long-term wealth building
- Children’s future education
- Leaving assets to future generations
Longer horizons can provide more time to tolerate market volatility, although that does not mean every long-term investor should take maximum risk.
Your risk tolerance, financial situation, and specific goal still matter.
Short-, Medium-, and Long-Term Goals at a Glance
| Goal | Typical Time Horizon | Primary Consideration |
|---|---|---|
| Emergency fund | Immediate to 1 year | Liquidity and stability |
| Credit-card debt payoff | Months to several years | Interest cost |
| Vacation | 6–18 months | Cash availability |
| Home down payment | 2–5+ years | Time horizon and capital preservation |
| College funding | 5–15+ years | Time horizon, risk, and education costs |
| Retirement | 10–40+ years | Long-term growth, inflation, and risk |
These are planning categories, not rigid rules. Your personal circumstances determine the appropriate time horizon for each goal.
Why Time Horizon Should Influence Your Investment Strategy
Consider two investors.
Investor A needs $50,000 in 18 months for a home purchase.
Investor B is 30 years old and is investing for retirement at age 65.
Both may have the same risk tolerance.
But their financial goals are fundamentally different.
If the stock market falls sharply next year, Investor A may have very little time to wait for a recovery.
Investor B potentially has decades.
This is why an investment portfolio should be evaluated in the context of the goal it is designed to fund.
Investor.gov explains that asset allocation should reflect both time horizon and risk tolerance, and that portfolios designed for short-term goals generally need less exposure to highly volatile assets than portfolios designed for much longer horizons.
How to Prioritize Multiple Financial Goals
Most households do not have just one financial goal.
You may want to:
- Build an emergency fund
- Pay off credit-card debt
- Save for a home
- Invest for retirement
- Save for your children’s education
- Travel
The challenge is that your income is limited.
You cannot necessarily maximize every goal simultaneously.
That means financial planning is partly an exercise in prioritization.
A Practical Goal Priority System
| Priority | Goal | Reason |
|---|---|---|
| 1 | Basic financial stability | Protects against unexpected financial shocks. |
| 2 | High-interest debt | Reduces expensive interest costs. |
| 3 | Near-term essential goals | Prepares for known upcoming expenses. |
| 4 | Medium-term goals | Funds major planned life events. |
| 5 | Long-term wealth and retirement | Builds future financial security. |
This is not a universal ranking that applies identically to every household.
For example, an employer retirement match may make retirement contributions valuable even while someone is paying down debt. Likewise, an individual with substantial emergency savings may be able to focus more heavily on long-term investing.
The important principle is to understand the trade-offs instead of treating every financial goal as equally urgent.
Emergency Savings Should Be a Financial Goal Too
Emergency savings are often overlooked because they do not feel like an investment.
But an emergency fund serves a different purpose.
Its job is not primarily to maximize returns.
Its job is to provide financial resilience when something unexpected happens.
Examples include:
- Job loss
- Major car repairs
- Unexpected medical expenses
- Urgent home repairs
- Temporary income disruption
The CFPB emphasizes emergency savings as an important part of financial well-being and notes that automatic transfers can make saving more consistent.
For many households, an emergency fund can prevent an unexpected expense from turning into high-cost debt.
Debt Repayment Can Also Be a Financial Goal
Financial planning is not only about investing.
If you have expensive consumer debt, reducing that debt can be an important financial objective.
For example:
“I will eliminate $18,000 of high-interest credit-card debt within 24 months.”
That is a measurable financial goal.
If debt is part of your financial situation, you may also want to review the debt avalanche method and compare the financial trade-off between paying down debt and investing.
How Much Should You Save Each Month?
The basic calculation is straightforward:
Monthly Savings Needed = Amount Still Needed ÷ Number of Months Remaining
Suppose you want $36,000 in three years and already have $6,000.
Your remaining target is:
$36,000 − $6,000 = $30,000
There are 36 months remaining:
$30,000 ÷ 36 = approximately $833 per month
This calculation does not assume investment returns.
That is intentional.
It gives you a simple baseline before introducing uncertain variables such as market returns, taxes, inflation, and fees.
What If You Include Investment Returns?
For longer-term goals, investment growth can materially change the amount you need to contribute.
Suppose you invest $750 per month for 20 years.
Your total contributions would be:
$750 × 240 months = $180,000
If the investments generate positive returns over that period, the ending portfolio value could be higher than your total contributions.
But there is an important caveat:
Investment returns are not guaranteed.
Actual results will depend on market performance, fees, taxes, investment selection, contribution timing, and other factors.
Therefore, long-term financial planning should use reasonable assumptions and stress-test different outcomes rather than depending on a single optimistic return forecast.
Nominal Dollars vs. Real Purchasing Power
Inflation can complicate long-term financial goals.
Imagine saying:
“I want $1 million for retirement.”
That sounds precise.
But $1 million decades from now may not have the same purchasing power as $1 million today.
For long-term planning, investors therefore need to distinguish between:
| Concept | Meaning |
|---|---|
| Nominal value | The dollar amount stated in future dollars. |
| Real value | The purchasing power after accounting for inflation. |
This is particularly important for retirement planning.
If your real objective is to maintain a certain standard of living, simply targeting a future dollar amount may not tell the whole story.
This is also why understanding how inflation affects your purchasing power is an important part of long-term financial planning.
How Income Growth Changes Your Financial Goals
A financial plan should not assume that your income will remain unchanged forever.
Career development, promotions, business income, professional skills, and other changes can affect your savings capacity.
| Approach | Example |
|---|---|
| Reduce expenses | Cut $300 of unnecessary monthly spending. |
| Increase income | Increase monthly after-tax income by $1,000. |
| Increase savings rate | Raise retirement contributions from 10% to 15% of income. |
| Automate contributions | Automatically transfer money after each paycheck. |
| Use windfalls intentionally | Direct part of bonuses or tax refunds toward specific goals. |
The goal is not simply to spend less forever.
It is to create a system in which your financial capacity improves over time.
A Real-Life Example: Building a Three-Level Financial Plan
Consider Alex, a 35-year-old professional in the United States.
Alex earns $100,000 per year and can currently save and invest approximately $1,500 per month.
Alex has three major goals:
| Goal | Target | Time Horizon |
|---|---|---|
| Emergency fund | $18,000 | 12 months |
| Home down payment | $80,000 | 5 years |
| Retirement | Long-term portfolio growth | 30 years |
Alex could make the mistake of treating all three goals identically.
But the goals have different time horizons.
The emergency fund needs liquidity.
The home down payment needs a balance between growth and protecting money needed on a known timeline.
The retirement portfolio has a much longer horizon and may be able to tolerate more short-term market volatility, depending on Alex’s overall circumstances and risk tolerance.
The key lesson is that the same investor can legitimately use different financial strategies for different goals at the same time.
The Goal Determines the Investment Horizon
This principle is worth repeating:
Do not start with the investment. Start with the goal.
Instead of asking:
“Should I buy stocks?”
Ask:
“When will I need this money?”
Then:
“How much volatility can I tolerate without jeopardizing the goal?”
Then:
“What type of portfolio is consistent with that time horizon and risk level?”
Investor.gov similarly emphasizes that asset allocation depends on time horizon and risk tolerance and that there is no single asset allocation that is appropriate for every financial goal.
Short-Term Goal vs. Long-Term Goal: Why the Difference Matters
| Feature | Short-Term Goal | Long-Term Goal |
|---|---|---|
| Time horizon | Months to a few years | Many years or decades |
| Liquidity need | Usually high | Usually lower in the early years |
| Ability to wait through volatility | Limited | Greater |
| Capital preservation | Often important | Growth may have greater importance |
| Potential investment choices | Cash, savings, short-duration or other lower-volatility options depending on circumstances | Potentially diversified stocks, bonds, and other long-term investments |
This does not mean stocks are automatically inappropriate for every short-term goal or that bonds are automatically appropriate for every long-term goal.
It means that the investment strategy should reflect the consequences of losing money when the money is needed.
Build a Financial Goal Pyramid
A useful way to organize your financial life is to think in layers.
| Layer | Objective |
|---|---|
| 1. Financial Stability | Emergency savings, essential insurance, cash-flow control |
| 2. Debt Management | Control high-cost debt and improve cash flow |
| 3. Short-Term Goals | Fund near-term planned expenses |
| 4. Medium-Term Goals | Prepare for home purchases, education, business, or other major goals |
| 5. Long-Term Wealth | Build retirement assets and long-term financial independence |
This framework helps prevent a common mistake: trying to build wealth aggressively while ignoring financial vulnerabilities underneath the portfolio.
Retirement Should Be More Than a Dollar Target
“I want $2 million by age 60” is better than “I want to retire rich.”
But even $2 million may not be enough information.
Retirement planning should also consider:
- Expected retirement age
- Annual spending needs
- Housing costs
- Healthcare expenses
- Taxes
- Social Security assumptions
- Other income sources
- Expected portfolio withdrawals
- Inflation
- Longevity
For U.S. investors, retirement accounts such as a 401(k), Traditional IRA, and Roth IRA may form part of the retirement strategy, depending on eligibility and individual circumstances.
The important point is that the account is not the goal.
Retirement security is the goal. The account is one of the tools used to pursue it.
Financial Freedom as a Long-Term Goal
Financial freedom is another goal that is often described too vaguely.
“I want to be financially free” sounds inspiring, but it does not tell you how much money you need.
A more useful approach is to calculate:
- Current annual spending
- Expected future spending
- Debt obligations
- Potential income sources
- Investment assets
- Desired financial margin of safety
You can then explore what level of invested assets might be required to support your desired lifestyle.
For a deeper framework, see our guide on how much money you may need for financial freedom.
What If You Have Too Many Goals?
This is extremely common.
Suppose your goals include:
- $15,000 emergency fund
- $50,000 home down payment
- $20,000 new car
- $25,000 student loan payoff
- $1 million retirement portfolio
- $10,000 travel fund
Trying to fund all of these equally may create a financial system that feels impossible.
Instead, classify them as:
| Category | Action |
|---|---|
| Essential | Protect and fund first. |
| High-cost | Evaluate expensive debt carefully. |
| Important | Fund systematically according to the deadline. |
| Flexible | Adjust when cash flow is tight. |
| Long-term | Automate and maintain consistency. |
Not every goal needs maximum funding every month.
The objective is to create a sequence that is sustainable.
The “Minimum, Normal, Ideal” Goal System
One useful technique is to create three contribution levels.
| Level | Monthly Contribution | Purpose |
|---|---|---|
| Minimum | $500 | Amount you can maintain even during difficult months |
| Normal | $1,000 | Your standard target |
| Ideal | $1,500 | Used when income or cash flow is stronger |
This approach can make your financial plan more resilient.
If you contribute $700 instead of $1,000 during one difficult month, the plan has not failed.
You simply operated below your normal contribution level.
Should You Change Your Financial Goals?
Absolutely.
A financial goal is not a contract with the future.
Your life can change.
You may:
- Change jobs
- Receive a promotion
- Start a family
- Move to another city
- Buy a home
- Take on new debt
- Receive an inheritance
- Experience a period of unemployment
- Change your retirement plans
When your circumstances change, your financial goals may need to change as well.
That is not failure.
It is financial planning.
How Often Should You Review Your Financial Goals?
A practical approach is to conduct a detailed review at least once a year, while monitoring major goals throughout the year.
Ask:
| Area | Question |
|---|---|
| Income | Has my income changed? |
| Expenses | Have my essential costs changed? |
| Debt | Has my debt balance or interest cost changed? |
| Savings | Am I saving at the planned rate? |
| Investments | Does my portfolio still match my goals and risk tolerance? |
| Goals | Have my priorities or deadlines changed? |
| Time horizon | Am I closer to needing the money? |
Investor.gov notes that changes in financial circumstances, risk tolerance, or the goal itself can be reasons to reconsider asset allocation.
Common Financial Goal-Setting Mistakes
1. Setting Too Many Goals
If everything is a priority, nothing is truly a priority.
2. Having No Deadline
“Someday” is not a useful planning date.
3. Ignoring Inflation
Long-term goals should consider future purchasing power rather than only today’s dollar amount.
4. Assuming Income Will Never Change
Your future savings capacity may increase or decrease.
5. Using Investment Returns to Make an Unrealistic Goal Look Affordable
Expected returns should not be treated as guaranteed income.
6. Choosing the Investment Before Defining the Goal
“I want to buy stocks” is not a financial goal.
“I need $1 million for retirement in 25 years” is a financial goal.
7. Copying Someone Else’s Financial Goals
Your friend’s home, car, retirement age, and portfolio size do not automatically make sense for your circumstances.
8. Ignoring High-Interest Debt
Building an investment portfolio while carrying expensive revolving debt can create an important financial trade-off that deserves analysis.
9. Forgetting Emergency Savings
Long-term investing becomes harder to maintain when every unexpected expense requires selling investments or taking on new debt.
10. Never Reviewing the Plan
Financial goals should evolve as your life evolves.
A Simple Financial Goal Worksheet
Use the following template to turn an idea into an actionable plan:
| Question | Your Answer |
|---|---|
| What is my goal? | |
| Why does this goal matter? | |
| How much money do I need? | |
| How much do I already have? | |
| When do I need the money? | |
| How many months remain? | |
| How much can I contribute each month? | |
| What risks could derail the plan? | |
| What financial account or investment vehicle fits the goal? | |
| When will I review the goal? |
Financial Goal Decision Table
| Your Situation | Planning Focus |
|---|---|
| No emergency savings | Build financial resilience and improve cash flow. |
| High-interest debt | Evaluate debt repayment as a priority. |
| Stable emergency fund | Increase focus on medium- and long-term goals. |
| Money needed within 1–2 years | Emphasize liquidity and protection of money needed for the goal. |
| Goal is 10+ years away | Evaluate long-term growth, diversification, and inflation. |
| Income is unpredictable | Consider larger cash reserves and flexible contribution targets. |
How Financial Goals Connect to Your Investment Plan
Once your goals are defined, you can begin connecting them to your investment strategy.
The sequence can look like this:
Life Goal → Financial Goal → Dollar Amount → Deadline → Time Horizon → Risk Capacity → Investment Strategy → Regular Contributions → Monitoring
This sequence is important because it prevents an investment product from becoming the starting point of your financial plan.
For example, instead of saying:
“I want to invest in an S&P 500 ETF.”
you might say:
“I am investing for retirement 25 years from now, I have a diversified portfolio, and this investment is one component of my long-term allocation.”
The second statement provides much more context.
How to Automate Your Financial Goals
Once a goal has been defined, automation can reduce the amount of willpower required to pursue it.
For example, you could arrange for part of each paycheck to flow automatically toward:
- Emergency savings
- 401(k) contributions
- IRA contributions
- Home savings
- Other designated financial goals
Automatic contributions can make saving more consistent because the decision does not have to be repeated every month.
The CFPB specifically highlights recurring automatic transfers as one way to make saving easier and more consistent.
Financial Goals and the Power of Consistency
Many investors focus heavily on investment returns.
But contribution consistency can be just as important for long-term planning.
Consider two investors.
Investor A spends months searching for the perfect investment but contributes irregularly.
Investor B uses a diversified strategy and automatically contributes $750 every month.
Neither investor knows exactly what the market will do next.
But Investor B has created a repeatable financial system.
That system can be more valuable than constantly trying to predict which asset will perform best next.
This is one reason a consistent saving system is an important part of long-term wealth building.
Financial Goals Should Support Financial Freedom
Financial freedom rarely comes from one enormous financial decision.
It is usually the result of many smaller decisions that compound over time:
- Controlling spending
- Managing debt
- Building emergency savings
- Increasing income
- Saving consistently
- Investing appropriately
- Managing risk
- Maintaining discipline
Each of these can become a separate financial goal.
For example:
| Long-Term Objective | Supporting Financial Goals |
|---|---|
| Financial independence | Build emergency savings, eliminate high-interest debt, invest consistently, increase income, control lifestyle inflation. |
| Early retirement | Increase savings rate, maximize eligible retirement accounts, build taxable investments, manage spending. |
| Home ownership | Build down payment, improve cash flow, manage credit, maintain closing-cost reserves. |
For a broader discussion, see our guide to financial freedom and life beyond financial dependence.
Frequently Asked Questions About Financial Goals
What is the difference between a financial goal and a financial plan?
A financial goal is a desired outcome, such as saving $50,000 for a home down payment. A financial plan is the broader system of actions used to achieve multiple goals.
How many financial goals should I have?
There is no universal number. A practical approach is to identify several long-term goals but limit the number of goals receiving maximum financial attention at the same time.
What are short-term financial goals?
Short-term goals are objectives that need to be funded relatively soon, such as emergency savings, debt repayment, or an upcoming major purchase.
What are medium-term financial goals?
Medium-term goals typically require several years and may include a home down payment, education, business capital, or another major planned expense.
What are long-term financial goals?
Long-term goals generally extend over many years or decades and can include retirement, financial independence, and long-term wealth building.
What is a SMART financial goal?
A SMART goal is Specific, Measurable, Achievable or Attainable, Relevant, and Time-bound. The framework helps turn a vague intention into an actionable objective.
Should investing be one of my financial goals?
Investing is generally a method for pursuing financial goals rather than the goal itself. Retirement, financial independence, or funding education are examples of underlying goals.
How much should I save each month?
The appropriate amount depends on your income, expenses, debt, existing savings, goal amount, and deadline. Start by calculating the monthly amount required to close the gap between your current resources and your target.
Should I invest money I need in two years?
Money needed on a short and defined timeline generally requires careful attention to liquidity and downside risk. A volatile investment may decline just when the money is needed.
Is a five-year goal considered long term?
There is no universal cutoff. Five years is often treated as an intermediate planning horizon, but the appropriate classification depends on the specific goal and how much flexibility you have around the deadline.
How does inflation affect financial goals?
Inflation reduces purchasing power over time. For long-term goals, the future amount needed may be substantially different from today’s nominal dollar target.
Should I prioritize debt repayment or investing?
It depends on the debt’s interest rate, your emergency savings, employer retirement match, tax situation, and investment plan. High-interest debt deserves particular attention because its cost can be substantial.
Should I have an emergency fund before investing?
An emergency fund can provide financial stability and reduce the need to sell investments or borrow money when unexpected expenses occur. The appropriate amount depends on your circumstances.
Can I change my financial goals?
Yes. Financial goals should evolve when your income, expenses, family situation, career, debt, or priorities change.
How often should I review my financial goals?
A detailed annual review is a useful starting point. Major life changes should trigger an additional review.
How do I calculate the monthly savings required for a goal?
A simple starting formula is: (Target Amount − Current Savings) ÷ Months Remaining. This ignores investment returns, taxes, inflation, and fees, which may need to be incorporated into more detailed planning.
Should retirement be my most important financial goal?
Retirement is important for many people, but the appropriate priority depends on individual circumstances. Emergency savings, expensive debt, housing, education, and other obligations may also matter.
Can financial goals help reduce financial stress?
A clear plan can make financial decisions more structured because you know what you are working toward and how today’s actions relate to future objectives.
What is the most important financial goal for beginners?
There is no universal answer. A beginner may first benefit from understanding cash flow, building emergency savings, managing expensive debt, and establishing a sustainable saving and investing system.
Final Thoughts: Start With the Destination, Not the Investment
Financial planning becomes much easier when you stop asking only, “What should I invest in?” and start asking, “What am I trying to accomplish with this money?”
A good financial goal has a destination.
It has a number.
It has a deadline.
And it has a reason.
Once those elements are clear, you can begin making better decisions about saving, investing, debt repayment, liquidity, and risk.
The most important principle is simple:
Goal first. Plan second. Investment vehicle third.
Your short-term money may need stability.
Your medium-term money may require a balance between growth and capital preservation.
Your long-term retirement assets may have more room for market volatility and long-term growth.
These are not contradictions.
They are consequences of having different financial goals.
You do not need a perfect forecast of the stock market to create a strong financial plan.
You need to know what you are trying to accomplish, how much it may cost, when you need it, and what actions you can consistently take today.
Over time, those individual actions can become something much more powerful than a list of financial wishes:
a financial system designed around the life you actually want to live.